6 Signs Your Restoration Company Has Outgrown Its Insurance Program
Growth changes more than revenue. A restoration company that adds reconstruction, mold work, contents packout, warehouse storage, employees, subcontractors, vehicles and larger commercial contracts can become a materially different insurance risk even when the same policies renew every year.
A restoration company has probably outgrown its insurance program when the business has materially changed but the structure, limits, classifications, endorsements and underwriting information behind its insurance have not changed with it.
Quick Answer
A restoration company has probably outgrown its insurance program when the operation has changed materially but the insurance program has mostly been renewed rather than redesigned.
A company that started with residential water mitigation may now perform mold remediation, sewage cleanup, reconstruction, contents packout, warehouse storage and larger commercial work while operating more vehicles and employing more people.
Bottom line: growth should trigger more than updated sales and payroll estimates. It should trigger a review of whether the policies, limits, classifications, endorsements, schedules and underwriting information still describe the company that exists today.
Key Takeaways
- Operational change is a stronger review trigger than revenue alone.
- Reconstruction, mold, sewage, packout and storage can create exposures that were not central to the original program.
- Customer-property limits should consider peak accumulation, not only the value of one average job.
- Fleet growth can create a need for more formal driver controls and accident procedures.
- North Carolina’s workers compensation rule generally begins at three or more employees, subject to statutory exceptions.
- Larger commercial contracts can expose missing limits or endorsements before a claim ever occurs.
Why Can Growth Change a Restoration Company’s Insurance Risk So Quickly?
Restoration businesses rarely become complex overnight. The change usually happens one decision at a time.
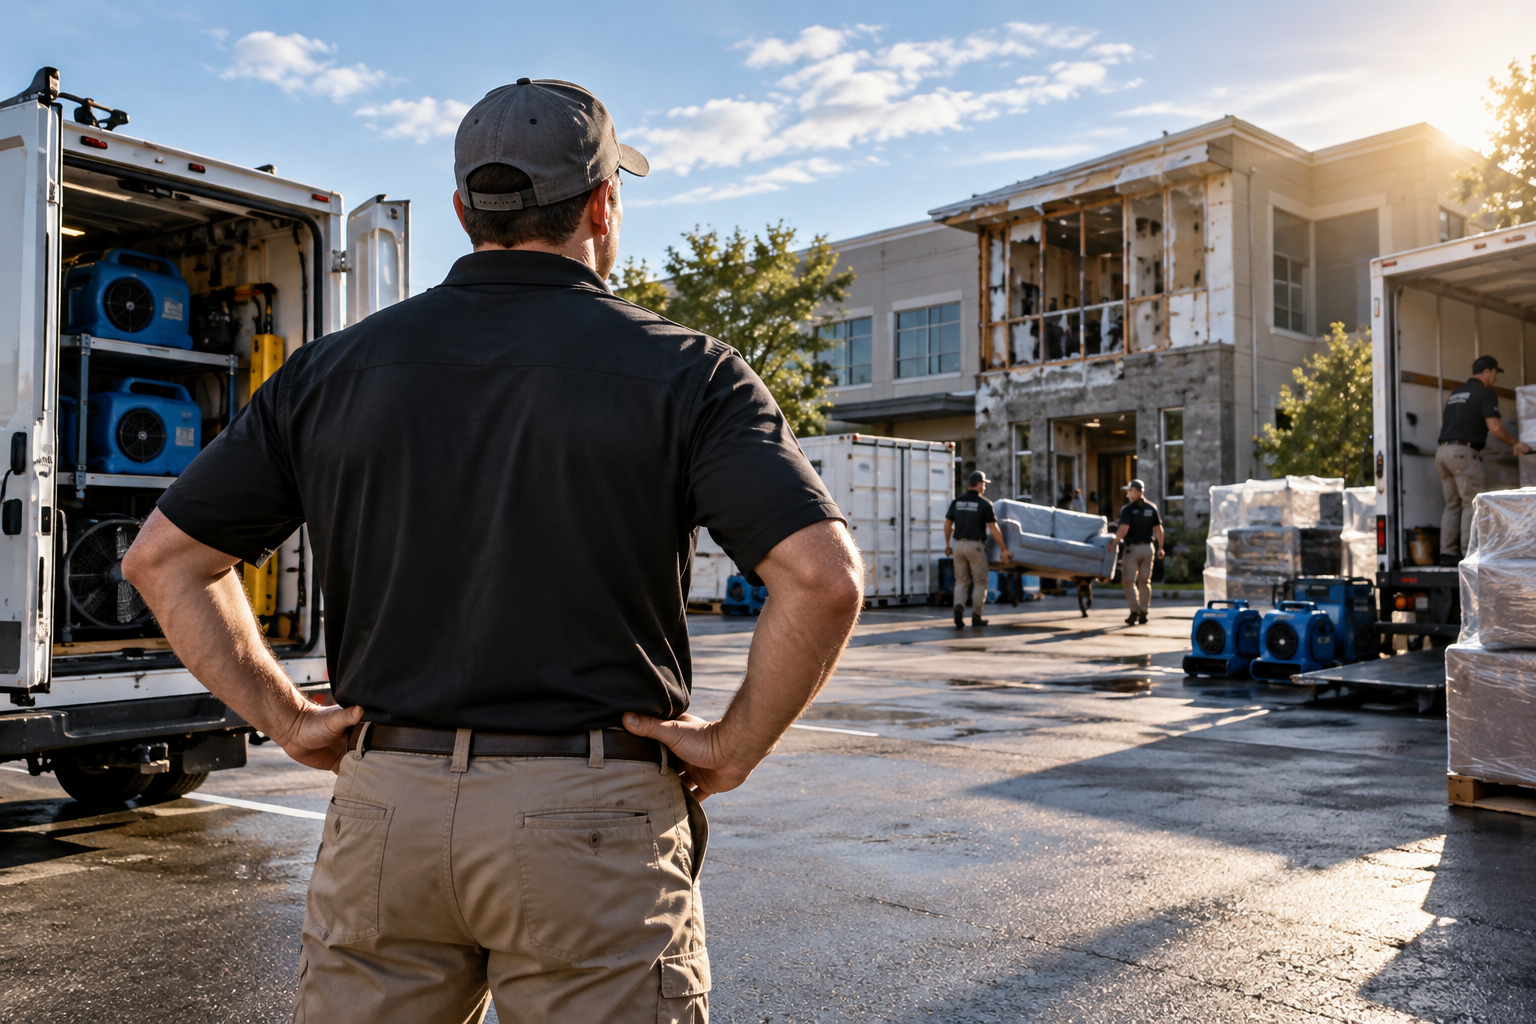
A few drying crews become multiple teams. Water mitigation expands into mold, demolition or reconstruction. The company begins moving customer contents, leases warehouse space, adds box trucks and starts handling larger commercial losses.
Eventually, the business being insured is materially different from the one originally submitted to the carrier.
That matters for restoration contractors throughout North Carolina, including companies growing in Wake Forest, Raleigh, Durham, Cary and the broader Triangle. Moving from homeowner losses into multifamily, property-management or commercial-facility work can change contract requirements, vehicle use, customer-property exposure and the amount of risk concentrated in any one job.
The question is whether the current insurance program was built around the company that exists today.
Has Your Service Mix Changed While Your Insurance Description Stayed the Same?
A restoration company may start with a relatively narrow operation such as water extraction and structural drying.
Growth can add:
- Mold remediation.
- Sewage and contaminated-water cleanup.
- Fire and smoke restoration.
- Demolition.
- Contents cleaning.
- Reconstruction.
- Emergency board-up.
- Temporary weather protection.
- Consulting or written recommendations.
Those operations are not automatically interchangeable from an underwriting or coverage standpoint.
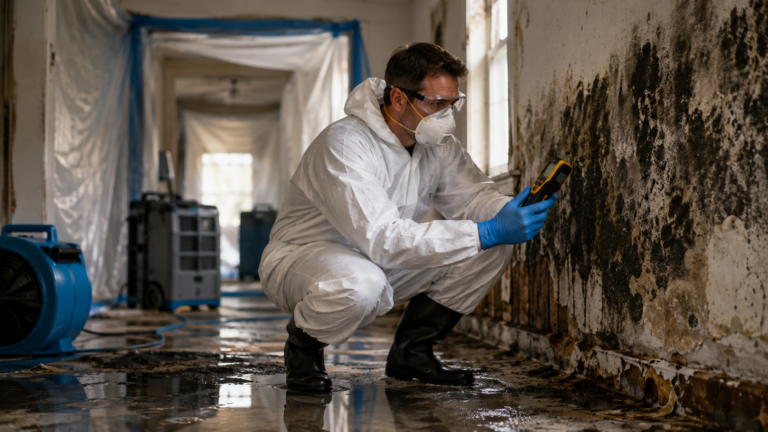
Pollution is one example. Restoration contractors intentionally encounter mold, bacteria, sewage, contaminated water, chemicals and damaged building materials. A general liability policy should not automatically be assumed to respond to every allegation involving those conditions.
If those services have become a larger part of the business, review the deeper guide on contractors pollution liability insurance for restoration companies.
Are You Holding More Customer Contents Than Your Program Was Built For?
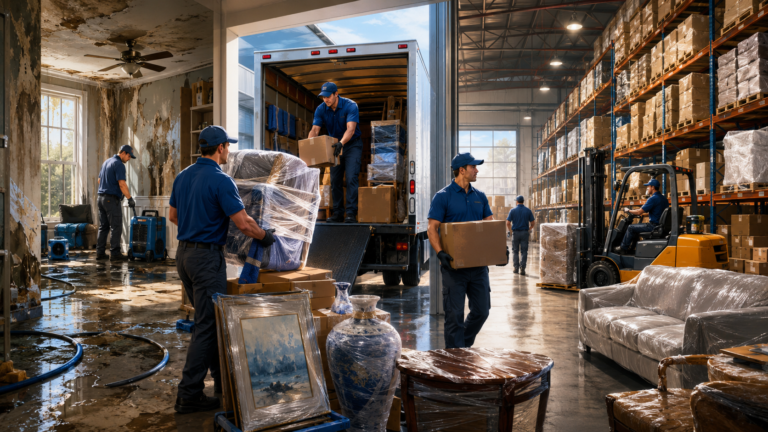
Packout changes the restoration company’s relationship to customer property.
Crews may inventory, remove, transport, clean, store and eventually return furniture, electronics, clothing, artwork, documents and other property belonging to multiple customers.
That number can be much more meaningful than the value of one average packout.
Exposure can increase further when the company adds:
- A dedicated contents division.
- A larger warehouse.
- Multiple simultaneous packouts.
- Box trucks dedicated to contents.
- Third-party cleaning vendors.
- Overflow storage locations.
- Higher-value commercial contents.
The review should look at customer property while being packed, transported, cleaned, stored and returned, along with policy limits, deductibles, valuation provisions and exclusions.
For the detailed issue, read Contents Packout and Storage: The Bailee Exposure Restoration Contractors Miss.
Has the Business Changed Faster Than the Insurance?
If you added services, vehicles, warehouse space, packout, employees, subcontractors or larger contracts, send me the basic situation. I can help identify which parts of the current program deserve a closer look.
I’ll follow up within 1 business day.
When Does a Restoration Vehicle Fleet Need More Formal Driver Controls?
Commercial auto becomes a different management problem as a restoration company scales.
A smaller business may have several vans driven by an owner and a few experienced employees. A larger operation may have pickups, cargo vans, box trucks, supervisors, technicians, estimators, project managers, trailers and employees taking vehicles home.
There is no North Carolina law saying a restoration company must adopt a particular fleet-management system at a specific vehicle count. The practical trigger is when management can no longer rely on informal knowledge of every driver and vehicle.
Management should be able to explain:
- Who is authorized to drive.
- When Motor Vehicle Records are reviewed.
- Which violations trigger management review.
- How accidents are investigated.
- How take-home vehicles are handled.
- Who may use rentals or temporary replacement vehicles.
- How box trucks and trailers are assigned.
- What happens when an existing employee no longer meets driver standards.
Restoration companies moving toward a managed fleet can also review North Carolina MVR standards and commercial auto insurance.
Has Your Workforce and Subcontractor Model Become More Complex?
Growing restoration firms may employ technicians, estimators, project managers, contents crews, reconstruction employees and supervisors while also using temporary labor and subcontractors.
That can change both workers compensation exposure and the information underwriters need.
North Carolina provides one clear legal benchmark: in general, businesses regularly employing three or more employees are covered by the North Carolina Workers’ Compensation Act, subject to statutory exceptions.
The North Carolina Industrial Commission specifically states that corporate officers count when determining whether a corporation reaches the three-employee threshold. The Commission gives the example of a corporation with two officers and one employee being required to provide workers compensation coverage. Corporate officers may be able to exclude themselves from policy coverage even though they still count toward the employee threshold.
Legal minimums are only one part of the review. Commercial clients can impose stricter insurance requirements, and subcontractor use can create additional workers compensation and liability concerns.
Management should ask:
- Are payroll estimates current?
- Do workers compensation classifications match the work being performed?
- How is reconstruction labor classified?
- How is temporary labor handled?
- Which scopes are subcontracted?
- Are subcontractor certificates and policies reviewed?
- Are subcontractor costs tracked accurately for audit?
- Do contracts impose specific insurance requirements on subcontractors?
Learn more about workers compensation insurance for North Carolina businesses.
Are Larger Clients Asking for Insurance Your Current Program Struggles to Provide?
Larger clients often reveal whether the insurance program has kept pace with the company.
Restoration firms in Raleigh, Durham, Cary, Wake Forest and elsewhere in North Carolina that move into multifamily, commercial property management, institutional facilities or larger vendor relationships may encounter insurance requirements that were uncommon when the business was smaller.
Requirements can include:
- Higher general liability limits.
- Umbrella or excess liability.
- Additional insured status.
- Completed operations additional insured status.
- Primary and noncontributory wording.
- Waiver of subrogation.
- Contractors pollution liability.
- Commercial auto requirements.
- Workers compensation and employer’s liability.
- Customer-property or bailee coverage.
- Insurance requirements imposed on subcontractors.
Primary and noncontributory: endorsement wording intended to make the contractor’s policy respond before specified additional-insured coverage and without seeking contribution from that additional insured’s policy, subject to the actual policy and endorsement.
Waiver of subrogation: an endorsement that may limit an insurer’s right to recover paid claim costs from a specified party when the policy and contract permit the waiver.
When every large contract creates a last-minute scramble for endorsements or limits, the issue may be larger than certificate processing.
The business may now be pursuing work that the existing program was never designed to support.
For the contract-specific issue, see Insurance Requirements in Commercial Property Management Restoration Contracts.
Does Your Renewal Process Still Look Like It Did When the Company Was Smaller?
This may be the strongest warning sign.
A restoration company can become dramatically more complex while the annual insurance process still consists primarily of:
- Updating estimated revenue.
- Updating payroll.
- Adding and deleting vehicles.
- Requesting loss runs.
- Renewing essentially the same policy structure.
Those administrative steps are necessary. They are not the same as reviewing the architecture of the insurance program.
Financial-document requirements also tend to depend on the account rather than one universal North Carolina revenue threshold. Depending on the carrier, coverage line, size of the account, rate of growth and underwriting concerns, an insurer may request additional financial information such as income statements, balance sheets, tax information or other financial documentation.
The useful question is not whether the company crossed an arbitrary revenue number. It is whether the operation has become complex enough that the insurer should be receiving materially different information than it received several years ago.
A mature program review can include:
- Current operations and service mix.
- Policy classifications.
- Pollution exposure.
- Customer-property values.
- Warehouse values.
- Tools and mobile equipment.
- Fleet controls.
- Workers compensation classifications.
- Subcontractor controls.
- Umbrella or excess limits.
- Contract requirements.
- Deductibles and retentions.
- Claims trends.
- Carrier appetite for the current operation.
What Do 2026 Insurance Market Conditions Mean for a Growing Restoration Company?
The 2026 market is a good example of why management should look at each coverage line separately instead of judging the renewal only by the total premium.
In The Council of Insurance Agents & Brokers’ Q2 2026 national commercial property and casualty survey, average premiums across all account sizes decreased 2.0%, but individual coverage lines moved in very different directions.
- Commercial property: average premiums decreased 6.3%.
- Workers compensation: average premiums decreased 3.2%.
- Commercial auto: average premiums increased 4.5%.
- Umbrella: average premiums increased 5.3%.
- Umbrella capacity: 40% of respondents reported decreased capacity.
North Carolina also has a specific 2026 workers compensation signal. The North Carolina Rate Bureau’s advisory loss-cost filing effective April 1, 2026 reflected an average 7.8% decrease statewide, with the contracting industry group decreasing 9.0%. The approved residual-market or assigned-risk filing reflected an average 7.6% rate decrease.
Those figures do not mean an individual restoration contractor’s workers compensation premium should decrease by the same percentage. Individual class codes vary, and final carrier pricing can also reflect loss-cost multipliers, experience modification, payroll, claims, schedule rating, carrier appetite and other factors.
The important point is that a restoration company’s property, workers compensation, auto and umbrella policies can be moving through different underwriting environments at the same time.
Sources: The Council of Insurance Agents & Brokers, Q2 2026 P&C Market Survey; North Carolina Rate Bureau Workers Compensation Rate Filings. Market-wide figures are not a guarantee of pricing for any individual account.
What Can Outgrowing an Insurance Program Look Like in Practice?
Consider an illustrative Wake Forest restoration company that began with several technicians, four service vehicles and mostly residential water mitigation, then expanded into commercial accounts throughout Raleigh and the Triangle.
Several years later, the company manages a larger driver population, operates a contents warehouse, uses box trucks, performs reconstruction and mold work, uses temporary labor and subcontractors, and services recurring commercial property-management accounts.
None of those changes automatically means the insurance is inadequate.
The concern appears when the insurance program still treats the business as essentially the same small water-mitigation contractor with larger sales and payroll.
The company now has materially different exposures involving:
- Environmental and pollution conditions.
- Customer property concentrated in storage.
- A larger driver population.
- More workers compensation exposure.
- Subcontracted reconstruction.
- Higher-value commercial contracts.
- Greater umbrella and excess liability concerns.
That is the difference between simply increasing policy values and redesigning an insurance program around a more complex company.
What Should a Growing Restoration Company Be Ready to Show Underwriters?
Growth itself is not necessarily a negative underwriting signal. Unexplained growth can be.
A strong submission should help an underwriter understand what changed and how management controls the exposure.
What operations are actually being performed?
Describe the current mix of mitigation, mold, fire, sewage, demolition, reconstruction, contents work and storage rather than relying on a generic restoration-contractor description.
How has payroll and the workforce changed?
Show current payroll estimates and identify meaningful changes in employee count, job duties, temporary labor or reconstruction activity.
What work is subcontracted?
Identify the scopes being subcontracted, approximate subcontractor costs and the insurance controls used before work starts.
How is the fleet managed?
Maintain an accurate vehicle and driver schedule and be ready to explain driver screening, MVR review, accident procedures and loss trends.
How much customer property can be in your custody?
Explain how packout, transportation, cleaning and storage operate, including the potential peak accumulation of customer property.
What does the loss history actually show?
Loss runs show what happened. A strong renewal presentation can also explain why it happened, what management changed afterward and whether current results support those corrective actions.
What are larger contracts requiring?
Commercial agreements can reveal whether current limits and endorsements match the work the company is trying to win.
What Can an Insurance Broker Change, and What Can a Broker Not Change?
A broker can help:
- Identify coverage questions created by growth.
- Improve how operations are explained to underwriters.
- Compare available carrier options.
- Review limits, deductibles, schedules and policy structure.
- Coordinate general liability, auto, workers compensation, pollution, property, inland marine and umbrella concerns.
- Review insurance requirements before larger contracts are signed.
- Identify which information underwriters are likely to request.
A broker cannot:
- Erase valid loss history.
- Guarantee that a carrier will quote or renew.
- Guarantee a lower premium.
- Make every exclusion disappear.
- Turn a certificate into coverage the policy does not provide.
- Override North Carolina law.
- Guarantee that a future claim will be covered.
What Should Be Included in a Restoration Insurance Program Review?
- What services do we perform today that we did not perform two or three years ago?
- How much of our operation is mitigation, reconstruction, mold, contents or other work?
- What is our peak accumulation of customer property?
- How many vehicles and regular drivers do we manage?
- Do we have written driver and accident procedures?
- Has employee payroll or job classification changed materially?
- How much work do we subcontract?
- What insurance do we require from subcontractors?
- Are warehouse locations and property values current?
- Are tools and mobile equipment schedules current?
- Do larger contracts require limits or endorsements we struggle to provide?
- Does the umbrella or excess structure coordinate with our underlying policies?
- Does pollution coverage match the contaminants and operations our crews encounter?
- Have recent claims exposed recurring operational problems?
- Are we asking insurers to cover the company we operate today or the company we used to be?
When Should a Restoration Company Trigger a Full Insurance Program Review?
There is no universal revenue, payroll or vehicle-count threshold that automatically means the insurance program is wrong.
The stronger trigger is material operational change.
A full review deserves consideration after:
- Adding a major service line.
- Adding reconstruction.
- Opening or expanding a contents warehouse.
- Increasing packout volume.
- Rapid fleet growth.
- Rapid payroll growth.
- Increasing subcontractor use.
- Expanding into larger commercial projects.
- Joining a preferred-vendor or national property network.
- Receiving more demanding contract requirements.
- A serious claim or repeated loss pattern.
- A major renewal increase or carrier restriction.
An established restoration company should not have to wait for a rejected contract, difficult audit, serious vehicle loss or uncovered claim before discovering that its insurance structure no longer reflects the business.
Frequently Asked Questions
How do I know if my restoration company has outgrown its insurance program?
A restoration company may have outgrown its insurance program when the business has materially changed through new services, employees, vehicles, subcontractors, customer contents, warehouses, larger projects or more demanding contracts but the insurance structure has not been redesigned around those changes.
Is there a specific revenue threshold where a restoration company needs a more sophisticated insurance program?
There is no universal North Carolina revenue or payroll threshold that automatically requires a different insurance program. Underwriting and financial-document requirements can vary by carrier, account size, operations, loss history, growth, property values, fleet exposure and contract requirements.
Does adding reconstruction change a restoration company’s insurance needs?
It can. Reconstruction may create different general liability, completed operations, workers compensation, subcontractor, equipment, contract and umbrella exposures than water mitigation alone.
What does peak accumulation mean for a restoration company’s contents exposure?
Peak accumulation is the highest total value of customer property the restoration company could have in its care, custody or control at one time across warehouses, vehicles, cleaning operations, temporary storage and other locations.
When is workers compensation generally required in North Carolina?
In general, North Carolina businesses regularly employing three or more employees are subject to the Workers’ Compensation Act, subject to statutory exceptions. Corporate officers are counted when determining whether a corporation reaches the three-employee threshold, although officers may be able to exclude themselves from policy coverage.
Who can review a restoration contractor insurance program in North Carolina?
Stephen Ellias, founder of Carolina Risk Partners and a Commercial Lines Coverage Specialist, helps North Carolina restoration contractors review commercial insurance programs, pollution coverage, workers compensation, commercial auto, customer property, umbrella limits and contract requirements. His North Carolina insurance license number is 20374030.
About Stephen Ellias
Stephen Ellias, CLCS, is the founder of Carolina Risk Partners LLC, an independent commercial insurance agency based in Wake Forest, North Carolina. He works with contractors and restoration companies on commercial insurance, workers compensation, fleet risk, pollution liability, customer-property exposures, contract requirements and renewal strategy.
North Carolina Insurance License 20374030
Has Your Restoration Company Changed?
If your business has added crews, vehicles, reconstruction, mold work, packout, storage, commercial contracts or other operations, the next renewal is a good time to make sure the insurance program still reflects the company you operate today.
This article provides general insurance information and is not legal advice or a determination that any specific policy will cover a particular claim or satisfy a particular contract. Coverage depends on policy forms, endorsements, exclusions, limits, deductibles, applications, underwriting and the facts of a loss. Contract interpretation and legal requirements should be reviewed with qualified legal counsel where appropriate.