When a High Experience Mod Starts Costing a Contractor More Than Workers Compensation Premium
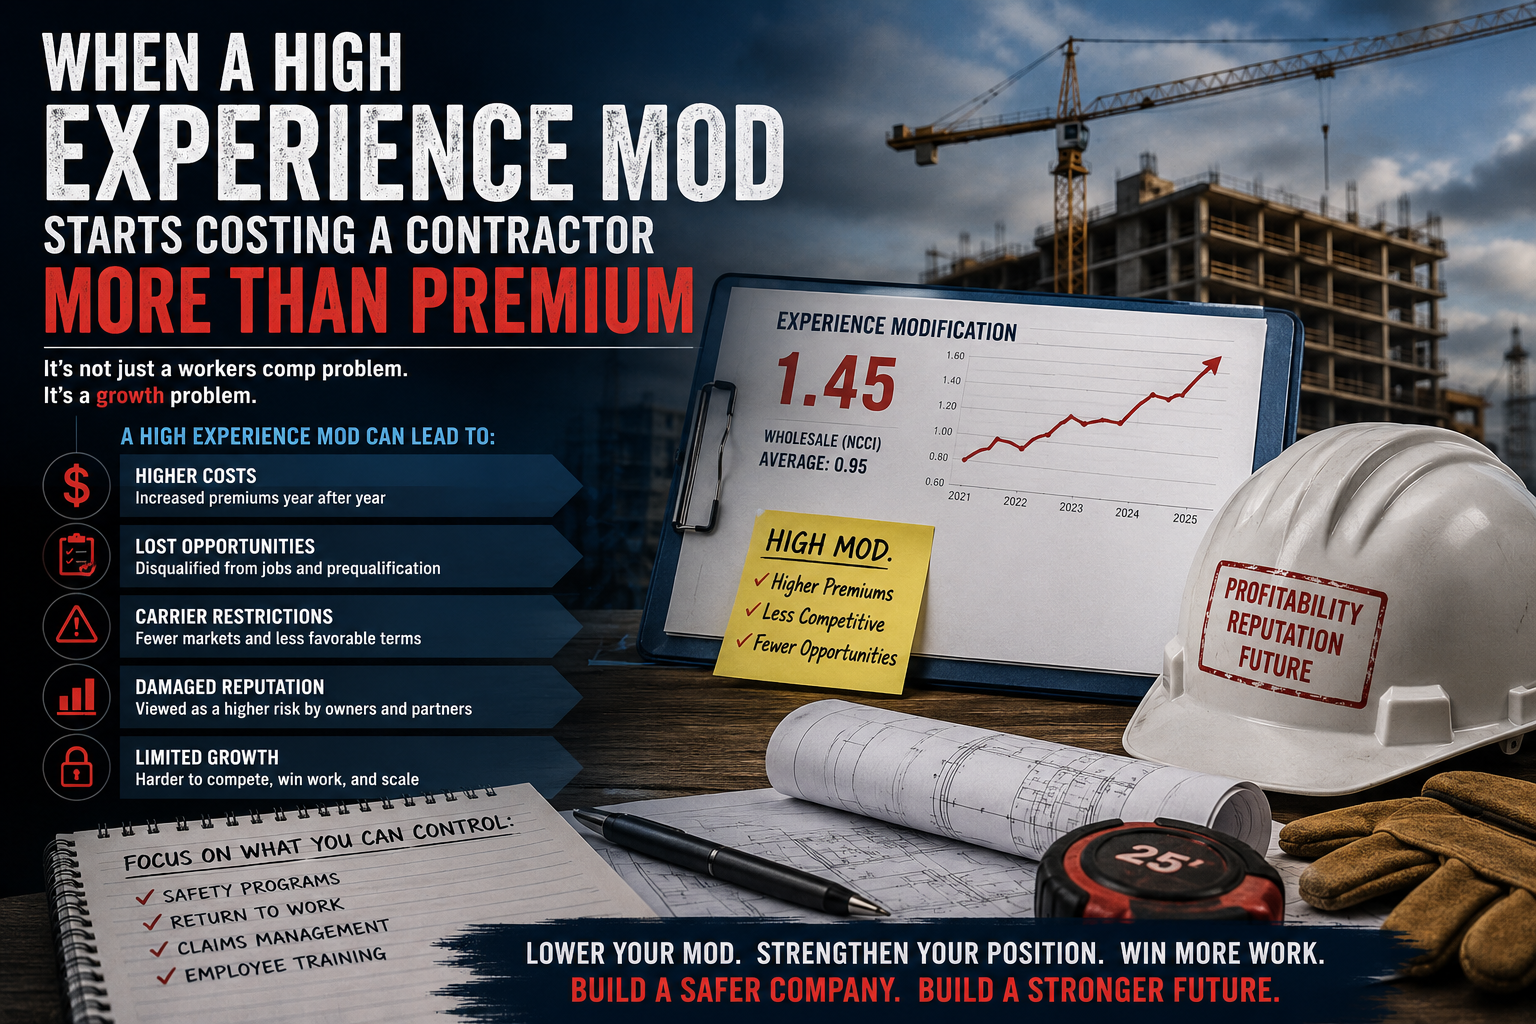
A high workers compensation experience mod can become a business-development problem. For an established contractor, the bigger cost may be tighter carrier options, harder prequalification, lost contract opportunities, and limits on how quickly the company can grow.
Key Takeaways
- A workers compensation experience mod above 1.00 is a debit modification in North Carolina and increases the premium to which the modification applies.
- For established contractors, premium may be only part of the financial impact.
- Project owners, general contractors, construction managers, and prequalification programs may consider EMR along with other safety information.
- A poor loss record can also affect workers compensation carrier appetite and renewal options.
- There is no universal North Carolina EMR cutoff that applies to every construction contract.
- The time to understand a bad mod is before renewal or prequalification, not when a bid deadline is already approaching.
Quick Answer
When does a high experience mod start costing a contractor more than workers compensation premium?
It happens when the mod begins affecting opportunities outside the insurance invoice. A contractor may still be able to buy workers compensation, but the same loss history can create problems with carrier appetite, owner prequalification, general contractor approval, bid eligibility, and access to larger projects.
Bottom line: once an experience mod begins interfering with the work a contractor wants to pursue, it has become more than an insurance pricing problem. It has become a growth problem.
Video: How a High Experience Mod Can Hurt Contractor Bidding in North Carolina
Stephen Ellias of Carolina Risk Partners explains how an elevated workers compensation experience mod can affect contractor prequalification, underwriting, carrier options, and access to larger commercial projects in North Carolina.
This video focuses on the business consequences of a high experience mod, including prequalification, loss-history questions, underwriting, carrier appetite, and contractor growth.
Experience Mod Contractor Bidding in North Carolina: The Premium Is Only the First Cost
Most contractors first learn about their experience modification rate because of workers compensation premium.
The North Carolina Rate Bureau explains that a credit modification below 1.00 decreases the premium affected by the mod, while a debit modification above 1.00 increases it.
But a growing contractor should ask a bigger question:
What else does this number prevent us from doing?
That is where an experience mod can become much more expensive.
If you are an established contractor pursuing larger commercial projects, institutional work, manufacturing facilities, municipal work, or larger general contractors, the equation changes.
Your experience mod can become part of the information other organizations use to evaluate whether they want to do business with you.
1. A High Mod Can Become a Contractor Prequalification Problem
Construction prequalification is not limited to whether a contractor carries the requested insurance limits.
Owners, general contractors, construction managers, and risk departments may evaluate financial capacity, project experience, safety programs, OSHA information, prior losses, and workers compensation experience.
Research from the Campbell Institute, summarized by the National Institute for Occupational Safety and Health, documented contractor prequalification practices that consider Experience Modification Rate along with other safety measures.
That matters because an insurance rating factor can effectively become part of a contractor’s business credentials.
Important: there is no universal North Carolina rule saying every contractor must have an experience mod below 1.00, 1.10, 1.20, or any other specific number to bid construction work.
Those standards are determined by the owner, general contractor, construction manager, or prequalification program.
This becomes especially important for contractors growing across the Triangle. A contractor moving from smaller local work into larger commercial projects in Raleigh, Durham, Cary, Wake County, or elsewhere in North Carolina may encounter more formal safety and subcontractor prequalification processes than it did earlier in its growth.
2. The Opportunity Cost Can Be Much Larger Than the Insurance Increase
Consider a simplified workers compensation example.
Illustrative contractor
Assume a contractor has $40,000 of workers compensation premium subject to the experience modification.
Illustrative difference: $14,000.
Fourteen thousand dollars is a meaningful workers compensation problem.
But suppose the same contractor is pursuing a multimillion-dollar commercial project and the prequalification process asks for several years of EMR history.
If that safety history becomes an obstacle to qualifying for the project, the financial issue is no longer limited to the $14,000 premium difference.
The larger issue is the opportunity the contractor may not be able to pursue.
A high mod can turn prior workers compensation losses into a constraint on future revenue.
This example is simplified and does not represent a quote or exact premium calculation. Actual premium can include other rates, credits, debits, assessments, expense charges, carrier pricing, and policy-specific factors.
3. Carrier Appetite Can Tighten Before Coverage Becomes Unavailable
A high experience mod does not automatically mean a workers compensation carrier will decline the account.
It also does not tell an underwriter everything they need to know.
But a deteriorating mod can be part of a larger underwriting story involving:
- Repeated claim frequency.
- A serious lost-time claim.
- Open claims with significant reserves.
- Rapid payroll growth.
- Higher-hazard class codes.
- Poor return-to-work results.
- Weak safety controls.
- Changes in operations.
- Unclear subcontractor practices.
- A lack of corrective action after losses.
Those factors can affect how many carriers are willing to quote, the competitiveness of the quotes received, loss-control requirements, deductibles, or other underwriting conditions.
For a larger contractor, that matters because a strong insurance program depends partly on having enough credible carrier options.
If the company outgrows the markets willing to tolerate its loss history, insurance can start interfering with expansion.
4. A Bad Mod Can Show Up at Exactly the Wrong Time
The worst time to discover an experience mod problem is when the estimator, CFO, safety manager, or owner is trying to finish a prequalification package due Friday.
At that point, the number is already what it is.
You may suddenly be trying to answer questions such as:
- Why did our mod increase?
- Which claims caused it?
- Why is a claim still open?
- Why is the reserve still this high?
- What safety changes did we make?
- Is the worksheet using the correct payroll?
- Are the class codes correct?
- Can we provide several years of verified EMR history?
- Is there an error that can actually be corrected?
- What can we truthfully tell the project owner?
Those are difficult questions to answer under a bid deadline.
For contractors moving into larger commercial work, experience-mod review belongs in the same planning conversation as workers compensation insurance, contract requirements, safety reporting, and broader contractor insurance.
5. Do Not Treat the Experience Mod as a Perfect Safety Score
An EMR is important, but it is not a perfect measurement of whether a contractor is safe today.
It is based on historical workers compensation payroll and loss experience, which means it is inherently backward-looking.
A contractor could have an older claim still influencing the mod even after management has changed procedures, improved training, implemented return-to-work practices, hired a safety professional, or made other operational improvements.
That is why sophisticated prequalification should look beyond one number.
It is also why a contractor with a poor historical mod should be prepared to explain the rest of the story.
A stronger explanation answers four questions
- What happened? Identify the type of losses affecting the experience.
- Why did it happen? Explain the operational issue without minimizing it.
- What changed? Document corrective action, training, procedures, supervision, or return-to-work improvements.
- What do the current results show? Provide updated loss information and current safety documentation where appropriate.
You cannot simply ask a rating bureau to ignore valid loss experience.
But you can keep an old claims problem from becoming an unexplained underwriting problem too.
Before the Next Bid Asks for Your Mod, Know What Is in It
If your experience mod increased, you have open workers compensation claims, or you are moving into larger commercial work, I can help review the insurance side of the problem before renewal or prequalification.
Stephen Ellias, CLCS, NC Insurance License 20374030. I’ll follow up within 1 business day.
6. North Carolina Contractors Large Enough for Experience Rating Should Treat the Mod as a Management Metric
Not every small contractor has an experience modification rate.
According to the North Carolina Rate Bureau’s current experience rating eligibility instructions, for rating dates beginning April 1, 2026, experience rating is mandatory when an employer meets the applicable premium threshold.
The listed eligibility thresholds are:
The exact experience rating rules and eligibility should be confirmed for the individual employer, particularly when multiple states are involved.
For a contractor large enough to develop a mod, that number deserves attention from more than the insurance department.
Ownership, operations, finance, estimating, safety, and business development can all have a reason to care about it.
7. What Should a Contractor Review Before the Mod Becomes a Bid Problem?
A productive experience-mod review is not simply asking the insurance agent, “Can you get this number down?”
Start with the underlying information.
8. Some Mod Problems Can Be Corrected. Some Have to Be Managed.
This distinction matters.
If the experience rating is based on valid payroll and valid losses, an insurance agent cannot simply negotiate the mod down because the number hurts.
But a detailed review may uncover information that deserves further investigation.
Examples can include:
- Incorrect payroll information.
- Incorrect class-code reporting.
- Ownership information that does not match the current business.
- Claim information that appears inconsistent with current loss data.
- Open claims that need an updated status review.
- Changes that may not have been reflected properly in the rating information.
Other problems are not errors.
A serious claim may simply be a serious claim.
When the data is correct, the strategy shifts from correction to management:
- Understand the experience-rating timeline.
- Improve claim management.
- Improve return-to-work procedures.
- Strengthen safety processes.
- Document corrective action.
- Prepare a credible underwriting explanation.
- Plan carrier marketing earlier.
- Know the prequalification requirements of target customers.
9. Growth Makes Experience Mod Management More Important, Not Less
A contractor can sometimes absorb a higher workers compensation bill.
What becomes harder to absorb is a restriction on where the company can go next.
Imagine a contractor that has spent years building:
- A stronger management team.
- More equipment.
- Larger crews.
- Better financial statements.
- More sophisticated estimating.
- Relationships with larger general contractors.
- The ability to perform larger projects.
Now the company is ready to move upmarket.
If an older workers compensation loss history becomes a repeated question during prequalification or underwriting, that history can begin working against the company’s current capabilities.
That does not mean the contractor is permanently stuck.
It means experience-mod management should become part of the company’s longer-term growth planning.
The larger the contractor becomes, the less useful it is to think of workers compensation as a policy that gets renewed once a year.
It is part of the operating record that customers, underwriters, and risk managers may use when evaluating the company.
10. When Should a North Carolina Contractor Get Ahead of the Problem?
Do not wait until the renewal proposal is already finished.
A good time to review the experience mod is when:
- The mod moves materially higher.
- A significant workers compensation claim occurs.
- A large claim remains open.
- The company is preparing to pursue larger contracts.
- A major GC adds new prequalification requirements.
- The company has grown substantially in payroll.
- Operations or class codes have changed.
- The business has undergone an ownership change or acquisition.
- Workers compensation carrier options are narrowing.
- The renewal needs to be marketed more aggressively.
For the mechanics of how the number itself is calculated, see our separate guide to the North Carolina experience modification rating and EMR calculation process.
This article answers the next question: what happens once that number starts interfering with the business?
Frequently Asked Questions
Can a high experience mod keep a contractor from bidding a job?
It can. Some project owners, general contractors, construction managers, and prequalification programs ask contractors to disclose their current or historical experience modification rates. The acceptable standard varies by organization and project, so there is no universal experience mod cutoff that applies to every contractor.
Is an experience mod above 1.00 considered high?
For North Carolina experience rating, the North Carolina Rate Bureau describes a modification greater than 1.00 as a debit modification. A debit modification increases the portion of workers compensation premium to which the mod applies. Whether an owner or general contractor considers that number unacceptable for prequalification is a separate decision.
Does a high experience mod affect workers compensation carrier appetite?
It may. Carriers evaluate more than the experience mod, but a poor loss history, open claims, claim frequency, severity, payroll changes, class codes, and safety controls can affect underwriting appetite, pricing, deductibles, loss control requirements, and available options.
Can my insurance agent lower my experience mod?
An insurance agent cannot simply choose a lower experience mod. A useful review can identify possible issues involving payroll, class codes, loss data, ownership changes, claim status, reserves, or reporting that may deserve further review with the carrier or North Carolina Rate Bureau.
How long can a bad workers compensation claim affect a contractor’s experience mod?
Experience rating generally uses historical payroll and loss information from prior policy periods, so the effect of a claim can continue beyond the policy year in which the injury occurred. The exact experience period and treatment depend on applicable experience rating rules and reported data.
When should a contractor review the experience mod?
Contractors should consider reviewing the experience mod before workers compensation renewal, before entering a major prequalification process, after a significant claim, after ownership or payroll changes, and before pursuing larger contracts where safety history may be reviewed.
Who can review a high experience mod for a North Carolina contractor?
Stephen Ellias, CLCS, North Carolina Insurance License 20374030, helps contractors review workers compensation experience modification worksheets, payroll and class-code information, loss runs, open claims, and renewal issues. If the review identifies information that appears incorrect or outdated, the next step may involve the workers compensation carrier, its reporting process, or the North Carolina Rate Bureau depending on the issue.
Primary Resources
About Stephen Ellias, CLCS
Stephen Ellias, CLCS, North Carolina Insurance License 20374030, is the founder of Carolina Risk Partners LLC, an independent commercial insurance agency based in Wake Forest, North Carolina.
He helps contractors throughout Raleigh, Durham, Cary, the Triangle, and North Carolina review workers compensation experience mods, loss runs, claims, audits, class codes, renewals, and contractor insurance programs.
When an experience mod looks wrong or is creating underwriting or prequalification problems, Stephen can help review the rating worksheet, payroll and classification information, and underlying loss data to identify items that may deserve further review with the carrier or North Carolina Rate Bureau.
Do Not Find Out Your Mod Is a Problem During a Bid
If your company is growing, pursuing larger contracts, or carrying a workers compensation loss history that is starting to create questions, review it before the next renewal or prequalification deadline.
This article is general insurance and risk-management information, not legal, accounting, safety, claims, or contract advice. Experience rating, workers compensation premium, carrier underwriting, and contractor prequalification depend on the employer, applicable rating rules, reported data, policy terms, loss experience, contract requirements, and the organization conducting the prequalification review.