

How Much Umbrella Insurance Should a Restoration Company Carry?
Compare $1 million in additional umbrella limits first. Growing restoration firms can also evaluate $2 million to $5 million; larger fleets, major commercial contracts or higher-severity operations may warrant comparing $5 million to $10 million or more. These are review tiers, not required minimums.
Umbrella limits should fit the actual contract, commercial auto exposure, completed operations and the underlying policies the umbrella follows.
No obligation to purchase. Start with your current policies and contract requirements.
Quick Answer: How Much Umbrella Insurance Does a Restoration Company Need?
Start with a $1 million additional umbrella limit as a comparison point. A growing restoration contractor should also evaluate $2 million to $5 million; larger or higher-severity operations may need to compare $5 million to $10 million or more. Contracts, realistic covered loss severity, underlying limits and exclusions determine whether any option fits.
Use these as review bands, not automatic recommendations. A $5 million contract requirement does not prove every restoration company needs a $5 million umbrella, and buying a $5 million umbrella does not mean every liability exposure has $5 million available.
For restoration companies in Wake Forest, Raleigh, Durham, Cary and the wider Triangle, review local and regional property-management contracts as well as actual vehicle and jobsite exposure. Geography alone does not prescribe a limit.
Key Takeaways
- Start with the highest limit required by your active contracts, then check whether that requirement applies to the umbrella, total liability limits, or a particular policy.
- Compare the contract requirement with your current general liability and commercial auto limits, but confirm the exact wording before calculating the layer you need.
- Fleet severity, reconstruction, completed operations, subcontractors, and larger commercial work can justify reviewing higher limits.
- Contractors pollution liability, professional liability, and bailee or customer-contents coverage may need separate limits. An umbrella does not automatically increase them.
- Confirm which policies the umbrella follows, the required underlying limits, attachment points, and any exclusions that affect restoration work.
For a North Carolina restoration contractor, an umbrella limit is not simply a number on a certificate of insurance. A $5 million limit can be useful over covered general liability and auto losses, but the form may not follow pollution liability, customer contents or professional exposures.
The useful starting point is the contract wording, the severity of the work your company actually performs, the underlying policy schedule and the limits already in force.
What Do Umbrella and Excess Liability Terms Mean?
Commercial umbrella liability insurance adds liability limits above selected underlying policies and may, on certain forms and terms, cover some claims not covered by the underlying insurance. Excess liability insurance adds a layer of limits above specified coverage; follow-form excess generally adopts the underlying policy’s terms subject to the excess form’s own provisions.
- Underlying insurance: the primary liability policies an umbrella or excess policy is written above.
- Attachment point: the level of applicable underlying loss or limits that must be reached before an excess layer can respond, subject to the policy.
- Follow-form: excess insurance that generally follows a specified underlying policy’s coverage terms, with any differences stated in the excess form.
- Completed operations: liability allegations arising from qualifying work after the contractor’s operations are finished.
- Contractors pollution liability (CPL): specialty liability insurance for certain pollution-related exposures from covered contracting operations, subject to its conditions and exclusions.
- Bailee or customer-contents coverage: protection that may address customers’ property while it is in the contractor’s care, custody or control, depending on the form.
These definitions explain the terms, not the scope of any particular policy. The actual forms control.
What Umbrella Limit Should a Restoration Contractor Compare First?
There is no single umbrella limit that fits every restoration contractor in North Carolina. A company doing limited residential water mitigation has a different risk profile from a regional operator with a large vehicle fleet, contents storage, mold remediation, reconstruction, and commercial vendor contracts.
Use the following bands to decide which options to price and compare. They are a starting framework for a coverage review, not a substitute for reviewing your own policies and contracts.
North Carolina does not set one universal $5 million umbrella requirement for every restoration contractor. The limit commonly comes from the specific contract, the insurer’s underwriting requirements, and the company’s own exposure and risk tolerance. Verify each contract rather than assuming a statewide rule applies.
North Carolina Restoration Contract Checklist: What Should You Read First?
This is a practical document-review worksheet for a restoration business pursuing commercial work in the Triangle or elsewhere in North Carolina. It is an original decision framework, not survey data, a claim example, or evidence that a particular carrier will approve a limit.
- Identify the contracting party. Is the requirement from a property manager, general contractor, facility owner, vendor program, or other client?
- Separate each required limit. Record general liability per occurrence and aggregate, commercial auto combined single limit, completed-operations requirement, and any separately stated umbrella or excess limit.
- Check whether limits may be combined. A contract requiring a $5 million umbrella is different from a contract allowing $5 million in total applicable limits.
- Check operations-specific language. Look for pollution, mold, professional services, customer contents, additional insured, primary and noncontributory, and completed-operations provisions where relevant.
- Compare wording to documents. Confirm the declarations, underlying schedule, policy forms, endorsements, and actual insurer approvals; a certificate alone is not a coverage grant.
Do not assume one standardized contract requirement applies throughout North Carolina. Contract language varies by customer and project.
How Do You Calculate the Preliminary Limit Gap in a Contract?
Read the insurance section of the actual contract first. Find the required general liability limit, commercial auto limit, umbrella or excess limit, and any special requirements for completed operations or additional insured status.
For example, imagine a vendor agreement expressly allowing $5 million in total applicable liability limits, and assume the particular exposure has $2 million of applicable primary limits. The preliminary $3 million difference identifies an option to investigate, not an automatic umbrella purchase. Per-occurrence and aggregate limits cannot be assumed to stack, and contract wording controls.
This is a hypothetical calculation, not a real client contract or claim. The arithmetic alone does not establish that a $3 million umbrella is available, appropriate, or contract-compliant. The policy forms, limits, endorsements, and wording must be checked.
If a contract calls for higher limits or your fleet, crews or reconstruction work has changed, send the basics. We can start with existing policies and the contract language.
Which Restoration Risks Should Push the Limit Review Higher?
The size of the company is only part of the picture. The better question is how severe a single covered event could become and whether the current insurance program responds to that event.
How Can More Vehicles and Drivers Change Umbrella Needs?
Restoration crews, estimators, supervisors, box trucks, service vans, and emergency-response vehicles spend time on the road. A serious auto loss can involve substantial injury, medical, legal, and property-damage costs. Review the fleet, driver population, vehicle use, radius, and current commercial auto limits together with the umbrella.
Why Do Larger Commercial or Institutional Contracts Affect Limits?
Multifamily portfolios, healthcare facilities, schools, hotels, commercial buildings, and national property-management relationships may impose specific limits and endorsements. Those requirements need to be checked against the actual agreement, not inferred from a certificate alone.
See the related guide: Insurance Requirements in Commercial Property Management Restoration Contracts.
How Does Reconstruction Increase Completed-Operations Exposure?
A company that moves from emergency mitigation into reconstruction can face a different liability profile. Some allegations may arise after the work is finished, so review completed-operations limits, subcontractor requirements, and the way the umbrella applies to those exposures.
Why Does Subcontractor Growth Matter to the Liability Tower?
More subcontracted work means more contracts, certificates, endorsements, and opportunities for gaps between what an agreement requires and what a policy actually provides. A certificate of insurance is evidence of certain policy information; it does not itself add coverage or replace the endorsement required by a contract.
Why Do Mold, Sewage and Pollution Operations Need Separate Review?
Contractors pollution liability (CPL) is specialty liability coverage designed to address certain pollution-related bodily injury, property damage, defense, cleanup, or restoration exposures arising from covered contracting operations, subject to the policy’s terms and exclusions. Restoration firms should not assume that an umbrella over general liability automatically increases CPL limits.
For more detail, read Restoration Contractor Insurance in North Carolina and Contents Packout and Storage: The Bailee Exposure Restoration Contractors Miss.
What Happens When More Customer Property Is in Your Care?
Bailee or customer-contents coverage addresses a different issue from the liability limits that an umbrella may extend. If your company packs, transports, cleans, or stores customers’ belongings, review the maximum value of customer property that could be in your care at one time and how it is insured at each stage.
What Does Current Liability Data Say About Higher Limits?
The Insurance Information Institute and Casualty Actuarial Society reported these national figures in November 2025. Commercial auto claim frequency fell over parts of the period, but claim severity rose substantially.
These are industry-wide figures, not restoration-specific claim results and not a forecast for any one company. They do not prove that every restoration contractor needs a particular umbrella limit. They do support reviewing fleet exposure instead of assuming the limit chosen several years ago remains appropriate.
Source: Insurance Information Institute, “Claims Severity Drives Liability Insurance Losses”, November 10, 2025.
How Much Does Commercial Umbrella Insurance Cost?
Umbrella pricing depends on the amount of coverage, industry, location, revenue, claims history, fleet, and which underlying policies the umbrella is intended to cover. Restoration-specific pricing cannot be reliably inferred from a broad small-business average.
These figures come from Insureon’s customers, many of whom have fewer than five employees. They do not establish a North Carolina restoration premium or what a multi-vehicle contractor would pay. Obtain operation-specific quotes for a reliable comparison.
Source: Insureon, Commercial Umbrella Insurance Cost, updated April 28, 2026.
For a meaningful comparison, request prices at more than one limit tier and compare the underlying requirements, exclusions, deductibles or retentions, and whether the umbrella follows the policies you expect. A lower premium is not necessarily the better result if the policy does not address the exposure that prompted the review.
What Is the Difference Between Umbrella and Excess Liability?
Both can add liability limits above primary insurance, but the terms are not interchangeable in every policy. The actual form, underlying schedule, and exclusions matter more than the product label.
For a carrier explanation, see Travelers’ commercial umbrella and excess liability overview and its explanation of excess liability.
What Does an Umbrella Policy Not Automatically Fix?
- Pollution or mold exclusions: A general liability umbrella does not automatically extend over contractors pollution liability.
- Professional services: Assessments, recommendations, consulting, protocols, or other professional services may require separate review.
- Customer contents: Property in your care, custody, or control may require bailee or other customer-property coverage.
- Missing endorsements: A certificate does not automatically provide additional insured, completed-operations, primary and noncontributory, or waiver-of-subrogation wording.
- Insufficient underlying limits: Umbrella policies often require the underlying policies to maintain specific limits. Those requirements need to be met.
- Contract wording: A higher limit alone does not prove the entire insurance section of a contract has been satisfied.
Review your commercial umbrella insurance coverage basics alongside general liability insurance and commercial auto insurance. The aim is to understand the structure, not just buy a larger number.
How Should You Choose and Revisit Your Umbrella Limit?
- Read the highest-limit contracts. Identify whether each one specifies an umbrella limit, a total limit, or separate limits for general liability, auto, employers liability, or completed operations.
- Map the underlying policies. List the policies scheduled under the umbrella and confirm their limits, attachment points, and required endorsements.
- Identify realistic severe-loss scenarios. Consider commercial auto, serious jobsite injuries, completed operations, subcontracted work, and any pollution-related exposures that may require separate coverage.
- Compare multiple limit options. Price the options that could meet the contract and exposure needs. Compare what each option covers, not only the premium.
- Revisit the decision when the business changes. A larger fleet, new contracts, reconstruction, more subcontractors, acquisitions, or new environmental services can change the risk picture.
Frequently Asked Questions About Restoration Umbrella Insurance
How much umbrella insurance should a restoration company carry?
For a growing restoration company, compare at least $1 million, $2 million to $5 million, and, where the exposure justifies it, $5 million to $10 million or more in additional liability limits. The right amount is the limit that fits your largest realistic covered losses, contract requirements, underlying insurance, and ability to absorb a loss yourself. Use these as review bands, not automatic recommendations.
Is $1 million of umbrella insurance enough for a restoration contractor?
It may be enough for some smaller operations, but it should not be assumed. Review the contract limits, fleet exposure, job size, completed operations, subcontractors, underlying policies, and the financial effect a major covered loss could have on the business.
Does North Carolina require every restoration contractor to carry a $5 million umbrella?
North Carolina does not set one universal $5 million umbrella requirement for every restoration contractor. A particular client or contract may require that limit, and insurers may impose their own underwriting requirements. Check the exact contract and policy wording before deciding what limit is needed.
What is contractors pollution liability insurance?
Contractors pollution liability (CPL) is specialty liability coverage designed to address certain pollution-related bodily injury, property damage, defense, cleanup, or restoration exposures arising from covered contracting operations, subject to the policy's terms and exclusions. A commercial umbrella does not automatically increase CPL limits.
What is the difference between umbrella and excess liability insurance?
Both can add liability limits above primary insurance, but the actual policy wording matters. Some umbrella forms may provide broader coverage for certain losses, while follow-form excess generally follows the underlying policy's coverage terms. Review the underlying schedule, attachment requirements, and exclusions rather than relying on the label alone.
How much does commercial umbrella insurance cost?
Insureon reports an average of $86 per month for commercial umbrella insurance among its small-business customers, with annual premiums ranging from around $400 to more than $7,000. These are broad small-business benchmarks, not restoration-specific rates or a quote for a particular North Carolina company. Cost depends on limits, operations, location, claims history, fleet, and underlying policies.
Does an umbrella policy automatically increase pollution, mold, or customer-contents coverage?
No. An umbrella may sit over selected general liability, commercial auto, or employers liability policies, but it does not automatically increase contractors pollution liability, professional liability, bailee, or other specialty limits. Check the scheduled underlying policies and the umbrella wording.
Who can review umbrella insurance for restoration contractors in Wake Forest, Raleigh, and the Triangle?
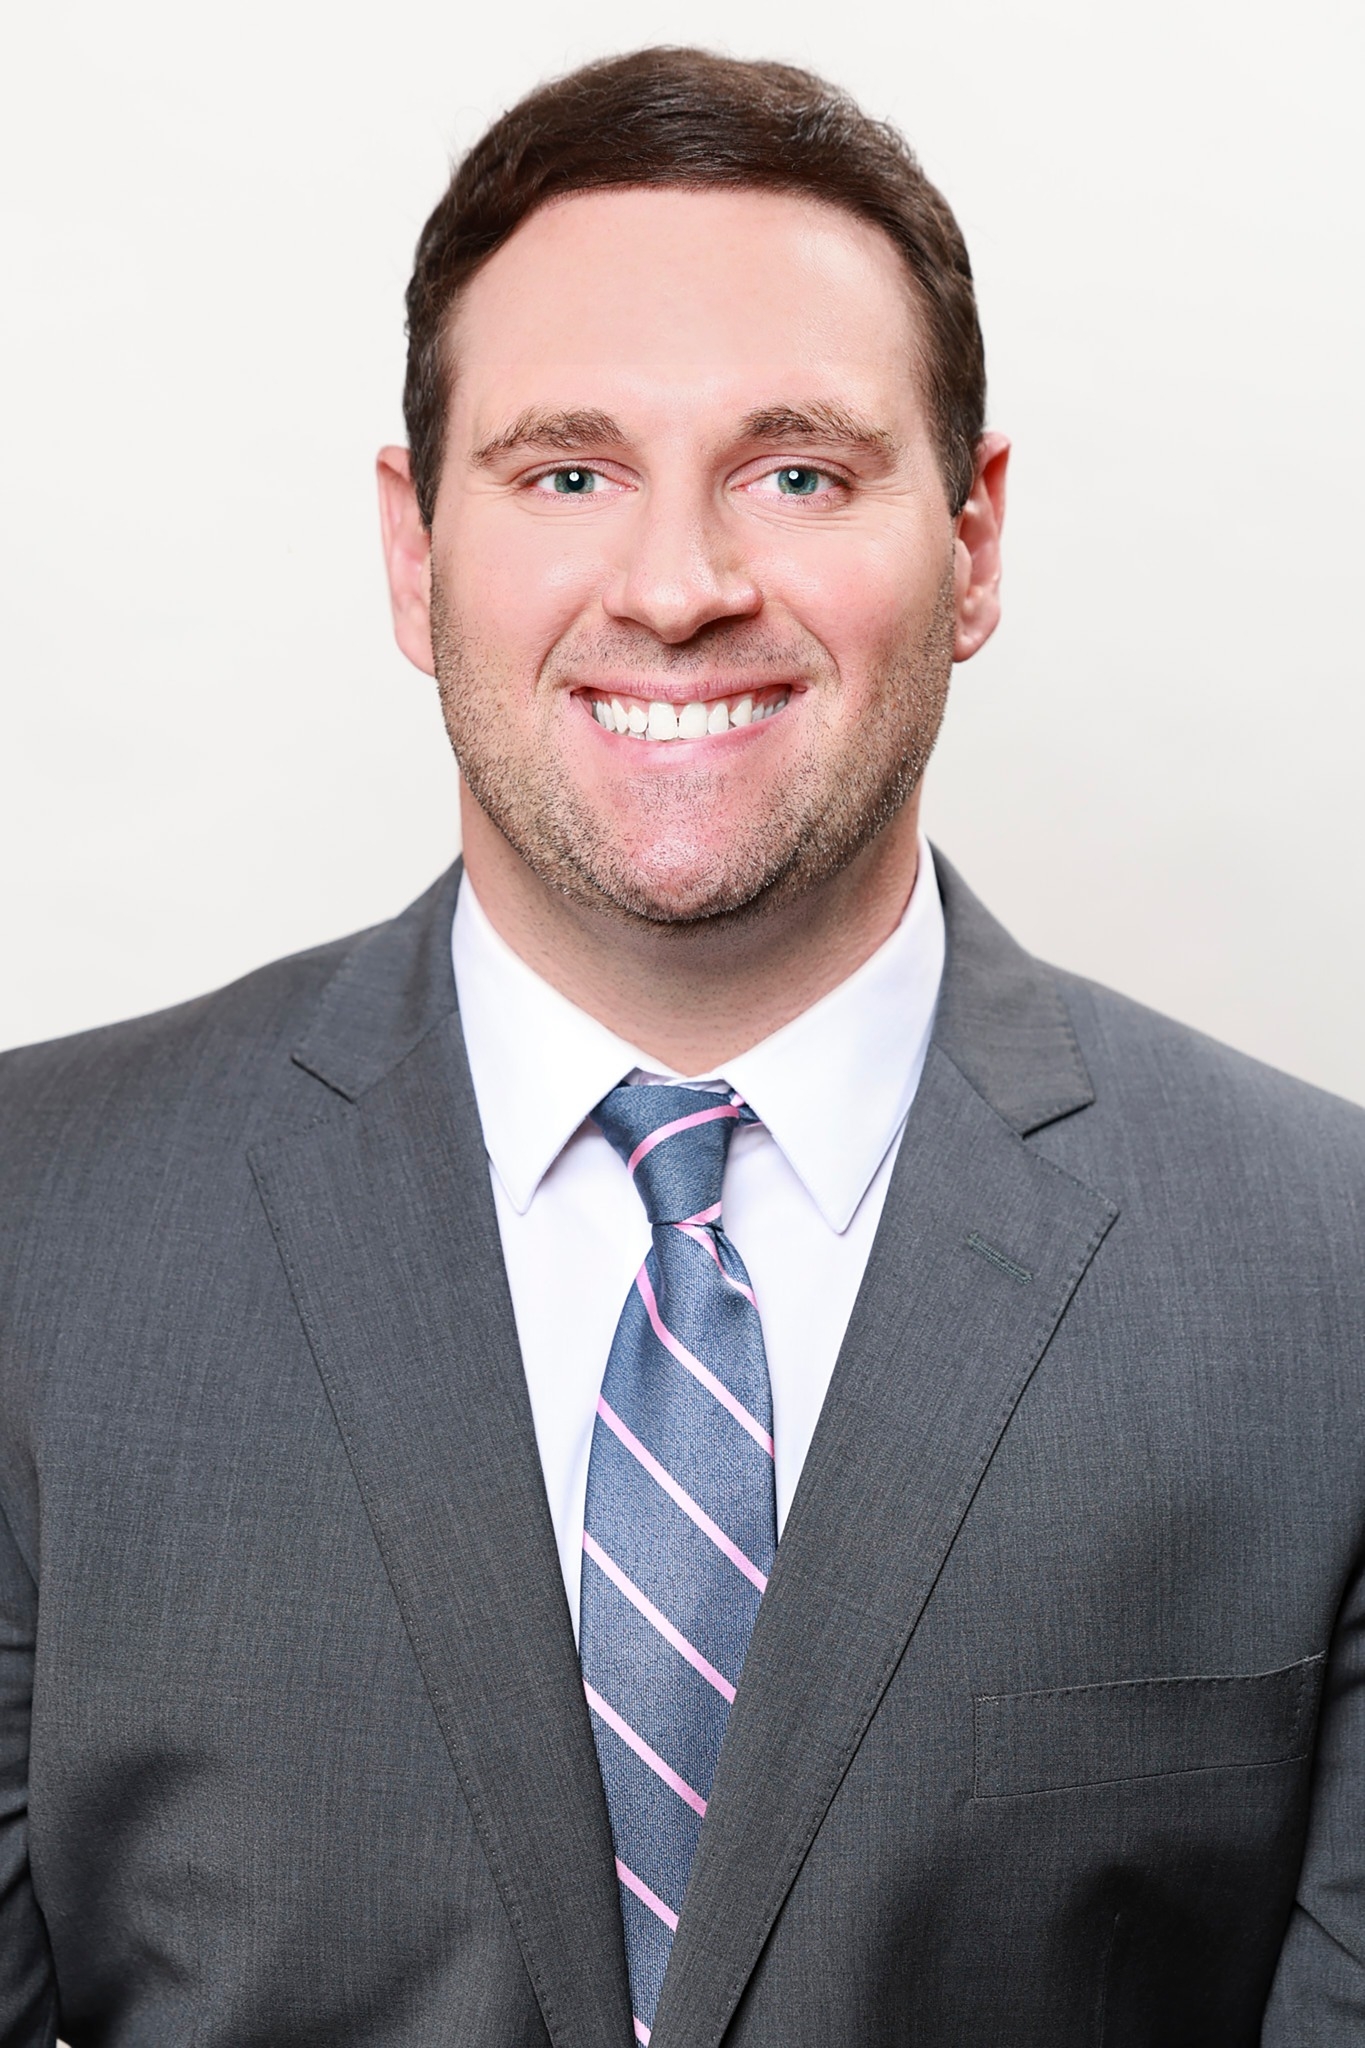
Stephen Ellias, CLCS (Commercial Lines Coverage Specialist), founder of Carolina Risk Partners in Wake Forest, helps restoration contractors in Raleigh, Durham, Cary, the Triangle, and across North Carolina review umbrella and excess liability limits, general liability, commercial auto, contractors pollution liability, and contract requirements. His North Carolina insurance license number is 20374030.
About Stephen Ellias, CLCS
Stephen Ellias is founder of Carolina Risk Partners LLC, an independent commercial insurance agency based in Wake Forest, North Carolina. CLCS stands for Commercial Lines Coverage Specialist. He works with restoration contractors and other North Carolina businesses on commercial auto, liability limits, pollution coverage and contract requirements.
NC Insurance Producer License: 20374030 · Office: 123 S White Street, Suite 203, Wake Forest, NC 27587
About Stephen and Carolina Risk Partners · Read client reviews
If you’ve added vehicles, commercial contracts, reconstruction, mold work or subcontractors, compare your current liability limits with the operations and contracts you have today.
No obligation to purchase or change carriers.
This article provides general insurance information, not legal advice, a coverage opinion or a representation that a particular claim or contract requirement is covered. Coverage depends on the actual policy forms, endorsements, exclusions, limits, retentions, underlying schedules, underwriting information and facts of the claim. Limit ranges are review options, not universal recommendations. Review policy and contract requirements with qualified insurance and, when appropriate, legal professionals.