

Does Insurance Cover Stolen Tools and Equipment on a Custom Home Site?
Yes, but not automatically. Builders risk may cover eligible building materials, while contractors equipment or inland marine coverage may insure eligible contractor-owned tools and machinery. Rented equipment and subcontractor-owned tools require separate consideration under the applicable policies and agreements.
Quick Answer: Which Policy Covers Stolen Tools?
The potentially relevant policy depends on the property. Builders risk may cover eligible building materials and property associated with construction. Contractors equipment or inland marine coverage may insure eligible contractor-owned tools and machinery. Rented equipment and subcontractor property need to be reviewed separately.
No policy label guarantees payment. Coverage depends on the actual wording, applicable endorsements, ownership, location, theft circumstances, and limits.
Key Takeaways for Custom Homebuilders
- Identify who owned the stolen property before deciding which policy to review.
- Check theft restrictions, unattended-property exclusions, security conditions, and sublimits.
- Document tools and equipment with receipts, photographs, serial numbers, and an inventory.
- Review coverage before starting a project or purchasing or renting expensive equipment.
Which Policy May Cover Each Type of Stolen Property?
A theft at a custom home site can involve property belonging to the homeowner, general contractor, subcontractor, or rental company. These differences matter because one policy may not insure every item on the project.
| Property stolen | Policy to investigate | What to verify |
|---|---|---|
| Lumber, windows, or other materials intended for the project | Builders risk or other applicable property coverage | Covered-property definition, storage location, transit terms, theft provisions, and limits. |
| General contractor’s tools or eligible machinery | Contractors equipment or inland marine | Eligible equipment, schedule requirements, theft restrictions, unattended-property conditions, and deductible. |
| Subcontractor-owned tools | Subcontractor’s equipment policy; potentially other applicable coverage | Ownership, insured status, contract responsibilities, and whether another policy expressly covers the property. |
| Rented excavator, lift, or other machinery | Applicable equipment coverage and rental-related insurance arrangements | Rental agreement, responsibility for loss, rented-property provisions, and exclusions. |
| Tools stolen from a truck or unsecured storage area | Potentially applicable equipment or property coverage | Vehicle and unattended-property wording, required security measures, theft conditions, and exclusions. |
| Damage to a building or other property during the theft | Potentially applicable property coverage; liability coverage if another party’s liability is alleged | Who owns the damaged property, what caused the damage, and the relevant policy terms. |
This table is a starting point for a coverage review, not a coverage determination. More than one policy may need to be examined, and the facts of the loss can change which provisions matter.
For broader context, see our business insurance and contractor insurance resources.
What Do Builders Risk, Inland Marine, and Contractors Equipment Mean?
What Is Builders Risk Insurance?
Builders risk is property coverage intended to protect a building under construction and certain covered materials, subject to policy terms. It does not automatically insure every contractor tool or piece of equipment at the site.
What Is Inland Marine Insurance?
Inland marine is a coverage category that can insure eligible property in transit, at temporary locations, or away from an insured premises, depending on the policy. Theft terms and restrictions still apply.
What Is Contractors Equipment Coverage?
Contractors equipment coverage, sometimes called an equipment floater, can insure eligible contractor tools and machinery at jobsites and other locations. Specific forms may contain theft sublimits, unattended-property restrictions, or exclusions.
A policy’s title is not enough to establish coverage. Review the insured property, ownership, location, applicable endorsements, exclusions, deductibles, and limits.
Does Builders Risk Cover Tools Stolen From a Custom Home Site?
Sometimes, but do not assume a builders risk policy covers every tool, piece of machinery, or item brought to a construction site. Builders risk generally focuses on covered property associated with the construction project. The specific policy determines which materials and other property qualify.
Eligible building materials intended for installation may be treated differently from a subcontractor’s tool chest, a general contractor’s portable compressor, or a rented excavator. Ownership and the policy’s definition of covered property are important.
When reviewing builders risk, check:
- Which building materials and other property qualify as covered property.
- Whether materials are covered at the site, in transit, or at temporary storage locations.
- Whether contractor-owned tools or machinery are included or excluded.
- Whether theft has specific restrictions, conditions, or exclusions.
- Whether the policyholder has an insurable interest in the stolen property.
- Which deductible and applicable limits would apply.
The homeowner, general contractor, and subcontractors may have different insurance arrangements. Do not assume the homeowner’s project policy insures every item brought to the site by every trade.
Does Contractors Equipment Insurance Cover Tools Stolen From a Jobsite?
Contractors equipment or inland marine coverage may cover eligible tools and machinery stolen from a jobsite. The result depends on the contract, the property involved, where it was located, and the circumstances of the theft.
Depending on the policy, eligible equipment may include generators, compressors, table saws, concrete equipment, and certain mobile machinery. Smaller hand tools may be covered, restricted, subject to a separate limit, or excluded. Confirm the policy language rather than relying on the coverage label.
Review these provisions in particular:
- Covered property: Does the policy include the stolen item and its owner?
- Location and territory: Does coverage apply at the project site and wherever the equipment was stored or transported?
- Theft conditions: Does the policy require evidence of forcible entry, a locked enclosure, or another security measure?
- Unattended-property exclusion: Is property left unattended, in a vehicle, or outside a secured structure restricted or excluded?
- Theft sublimit: Is there a specific maximum payable for theft or for certain tools in particular circumstances?
- Deductible and valuation: What deductible applies, and how is the item valued under the policy?
These are policy-review questions, not universal requirements. One policy may contain a condition that another does not, and endorsements may change the result.
General contractors managing several trades can also review our general contractor insurance resource when evaluating the wider insurance program.
Who Insures Subcontractors’ Tools Stolen From a Custom Home Site?
The subcontractor’s own equipment coverage is an important starting point when tools belong to an electrician, plumber, HVAC contractor, framer, or another trade. However, the correct answer depends on ownership, the policies in force, and the agreements between the parties.
A general contractor should not assume that its own contractors equipment policy automatically covers every subcontractor’s tools. Likewise, a subcontractor should not assume that the homeowner’s builders risk policy covers property the subcontractor brought to the site.
Before work begins, clarify:
- Who owns each category of tools, equipment, and materials.
- Who is responsible for securing equipment overnight.
- Which party must insure rented or subcontractor-owned equipment.
- Whether the written agreement addresses theft, loss, and responsibility for damaged property.
- Whether the relevant policies contain limitations for property belonging to others.
Contract terms and insurance policies serve different purposes. A contract may assign responsibility between the parties, but it does not by itself change the coverage terms of an insurance policy.
Does General Liability Insurance Pay for Stolen Tools or Equipment?
General liability insurance is not generally designed to insure a contractor’s own tools against theft. It primarily addresses covered liability claims for bodily injury, property damage, and other exposures defined by the policy.
If equipment is stolen, start by identifying the property owner and reviewing applicable property or equipment coverage. If the theft also involves damage to someone else’s property or a dispute over responsibility, liability questions may arise, but the facts and policy wording determine whether a liability policy responds.
Do not treat a general liability policy as a substitute for reviewing contractors equipment, inland marine, builders risk, or other potentially relevant property coverage.
Will Insurance Cover Project Delays After Tools or Materials Are Stolen?
A theft can interrupt work if a crew cannot continue without the missing tools, machinery, or building materials. Whether insurance covers the resulting delay or additional expense depends on the relevant coverage and the specific loss.
Coverage for stolen property and coverage for project interruption are separate questions. Do not assume that payment for stolen materials or equipment automatically reimburses schedule delays, additional labor, rental replacement equipment, or other knock-on costs.
When reviewing a possible delay-related claim, identify:
- What physical property was stolen or damaged.
- Which policy, if any, covers that property.
- Whether the policy contains coverage for relevant extra expenses or interruption losses.
- Whether any required insured event, waiting period, limit, or exclusion applies.
- Which costs are documented and directly connected to the loss.
Keep invoices, rental receipts, revised schedules, and records of additional costs. Ask the insurer to explain whether any delay-related expense is potentially covered under the actual policy.
Why Might an Insurance Company Deny or Limit a Stolen-Tools Claim?
A theft report does not automatically establish coverage. A claim may be declined or limited if the policy does not insure the property or if an applicable exclusion, condition, or limit affects the loss.
- The item is not covered property. The policy may not insure that category of tool or equipment.
- The ownership or insured interest is unclear. The property may belong to a subcontractor, rental company, homeowner, or other party.
- A theft exclusion or condition applies. The policy may restrict coverage in particular storage arrangements or circumstances.
- A security requirement was not met. A policy may impose a specific locking or protection condition.
- A limit or theft sublimit applies. The amount payable may be capped even if the loss otherwise qualifies.
- The loss is inadequately documented. Missing inventories, receipts, serial numbers, or ownership records may make it harder to establish the loss.
- The deductible reduces the payment. A covered loss may fall near or below the applicable deductible.
If a claim is declined or limited, ask the insurer to identify the policy provisions supporting its decision. Evaluate those provisions against the facts of the loss and the applicable policy documents.
How Could a Tool Theft Affect a Wake Forest Custom Home Project?
Illustrative example only—not an actual claim or a statement about a specific insurer: A custom home is under construction in Wake Forest. Overnight, someone steals a general contractor’s table saw, a subcontractor’s tool kit, and a package of building materials intended for installation.
The builder should not treat the missing property as one undifferentiated loss. Instead, separate the items by ownership and coverage:
- The table saw: Identify its owner and review the applicable contractors equipment or inland marine policy.
- The subcontractor’s tool kit: Confirm the subcontractor’s equipment coverage and review any relevant contractual responsibilities.
- The building materials: Review the builders risk policy and its terms for covered materials, storage location, and theft.
- Any site damage or additional costs: Document these separately and ask whether a relevant policy addresses them.
The builder should then document the theft, preserve available evidence, notify the appropriate parties, and submit information to the relevant insurer or insurers. No payment outcome can be predicted without reviewing the policies and facts.
What Should You Do After Tools or Equipment Are Stolen?
After a theft at a custom home project, prioritize safety, report the incident, preserve evidence, and notify the parties whose policies may apply.
- Report the theft. Contact local law enforcement and retain the incident or report number when available.
- Document the scene. Photograph damaged locks, gates, storage containers, vehicles, and other relevant conditions before making non-emergency changes.
- Create an itemized inventory. Record each missing item, its owner, make, model, serial number, age, and estimated value.
- Collect ownership records. Gather receipts, invoices, rental agreements, equipment schedules, and available photographs.
- Notify the relevant parties. Contact the policyholder, general contractor, property owner, subcontractor, rental company, or other party as appropriate.
- Review potentially applicable policies. Identify builders risk, contractors equipment, inland marine, and any other potentially relevant coverage.
- Contact the insurer promptly. Follow the policy’s notice requirements and cooperate with reasonable documentation requests.
- Keep a claim record. Save correspondence, claim numbers, estimates, receipts, and notes from conversations with insurers.
Preserve potential evidence. Before discarding damaged locks or other evidence, check with law enforcement and the insurer. Take reasonable steps to secure the site and prevent further loss.
How Can Custom Homebuilders Reduce Tool and Equipment Theft Risk?
A consistent prevention process can reduce avoidable exposure and make it easier to document property if a theft occurs. No security measure can guarantee that a site will be protected.
- Maintain a current inventory with serial numbers, photographs, and proof of ownership.
- Secure tools and portable equipment in locked containers or buildings when not in use.
- Establish end-of-day procedures for securing the jobsite.
- Consider lighting, access control, cameras, alarms, or other measures appropriate to the project.
- Record which contractor or subcontractor owns or controls equipment brought to the site.
- Review overnight storage arrangements and equipment transported between sites.
- Check policy limits and theft restrictions when buying or renting equipment.
- Make sure the project team knows how to report theft and preserve evidence.
Security procedures should be consistent with the actual conditions in the applicable policy. If a policy requires particular protections, confirm what those requirements mean for the way your crews store equipment.
What Should You Check Before the Next Custom Home Project?
Reviewing coverage before work starts gives the builder and relevant trades time to identify gaps or questions. Gather the current policies and compare them with the property that will be used, stored, rented, or transported.
- Current builders risk policy and endorsements.
- Contractors equipment or inland marine policy and equipment schedules.
- An inventory of higher-value tools and machinery.
- Rental agreements and records identifying responsibility for rented equipment.
- Subcontractor agreements addressing property, theft, and responsibility for loss.
- Storage arrangements and applicable policy security conditions.
- Deductibles, theft sublimits, valuation provisions, and exclusions.
- Procedures for documenting and reporting theft at each active site.
If you’re unsure which policy addresses an exposure, ask for the relevant policy wording to be reviewed. A general statement that a project is insured is not a substitute for confirming how specific property is treated.
Frequently Asked Questions About Stolen Tools and Equipment Insurance
Does builders risk insurance cover stolen tools?
Not automatically. Builders risk is intended to cover a building under construction and certain covered property, subject to the policy. Contractor-owned tools and equipment may require separate coverage. Check the covered-property definition, theft terms, exclusions, and limits.
Does inland marine insurance cover tools stolen overnight?
It may, depending on the policy, insured property, storage location, and circumstances of the theft. Review unattended-property restrictions, security requirements, theft sublimits, and exclusions that apply to overnight storage.
Are subcontractors’ tools covered by the general contractor’s policy?
Not necessarily. Coverage depends on the policy wording, ownership of the tools, and whether the general contractor has an insured interest in the property. Subcontractors should verify their own equipment coverage and review contractual responsibilities before work begins.
Does general liability insurance pay for stolen tools?
General liability is not generally designed to insure a contractor’s own tools against theft. It primarily addresses covered liability claims defined by the policy. Review applicable property or equipment coverage for the stolen items and consider liability coverage separately if another party’s property damage or liability is involved.
Will insurance cover project delays after tools or materials are stolen?
Do not assume that coverage for stolen property also pays for project delays, replacement rentals, additional labor, or other extra expenses. Review whether the applicable policy includes relevant interruption or extra-expense coverage and whether the loss meets its terms.
Does insurance cover tools stolen from an unlocked truck at a jobsite?
Coverage cannot be assumed. Some policies restrict or exclude theft from unlocked vehicles or unattended property, while others may apply different conditions. Check the exact policy and endorsements before concluding that the loss is covered or excluded.
What is an unattended-property exclusion?
An unattended-property exclusion or restriction limits coverage in specified circumstances when property is left without the required supervision or protection. The exact definition and effect vary by policy. Read the applicable wording to determine what counts as unattended property and what conditions must be met.
What is a theft sublimit?
A theft sublimit is a maximum amount payable for a specified theft-related category or circumstance, even if the policy’s overall limit is higher. Whether a sublimit applies, and the amount available, must be confirmed in the policy and endorsements.
Who can review contractor equipment coverage for a custom homebuilder in Wake Forest or Raleigh?
Stephen Ellias, CLCS, North Carolina insurance license 20374030, at Carolina Risk Partners in Wake Forest, North Carolina, can review relevant policy wording, equipment categories, theft restrictions, limits, and deductibles with a contractor. The review can help identify how the current policy addresses the exposure and what questions may need to be resolved with the insurer. Coverage cannot be guaranteed without reviewing the applicable terms and facts.
What records should I keep in case tools are stolen from a construction site?
Keep an inventory with descriptions, serial numbers, photographs, purchase receipts, invoices, and ownership details. Retain rental agreements, equipment schedules, security records, police report details, and insurer correspondence. These records can help establish what was stolen and support the claim review.
Are Your Tools and Equipment Properly Insured?
Custom homebuilders in Raleigh, Wake Forest, and across North Carolina should know how their policies address building materials, contractor-owned tools, rented machinery, subcontractor property, and theft at active jobsites.
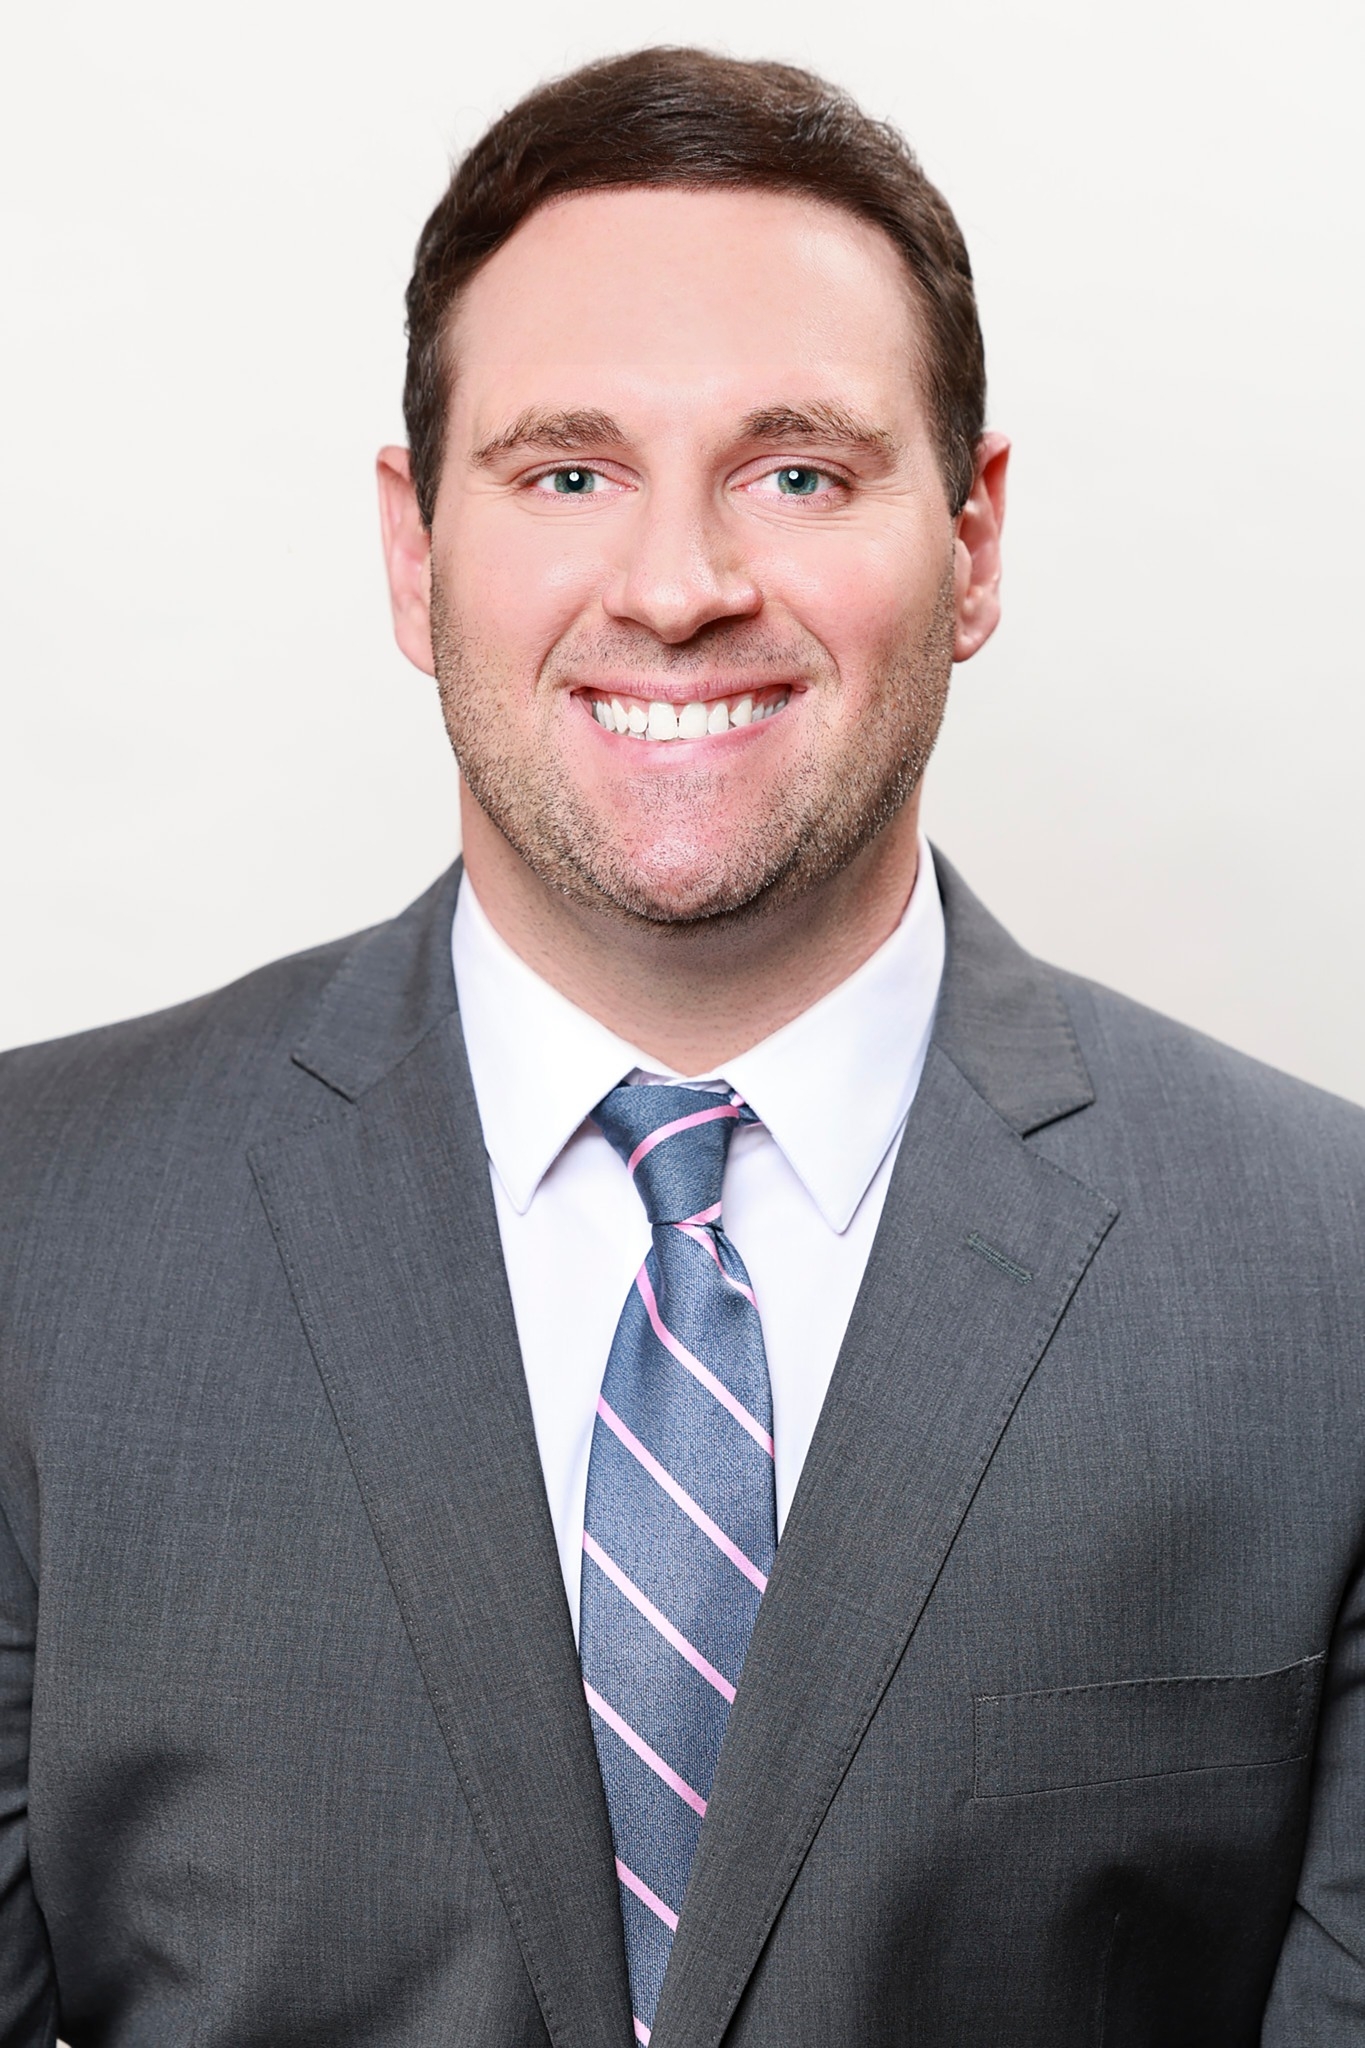
About the Author: Stephen Ellias, CLCS
Stephen Ellias holds the CLCS designation and North Carolina insurance license 20374030. Through Carolina Risk Partners in Wake Forest, North Carolina, he helps businesses evaluate commercial insurance questions, including how policy terms relate to their operations and property exposures.
This article provides general educational information, not a coverage determination. Actual coverage depends on the policy, endorsements, facts of the loss, and insurer’s claim review.
Review Your Jobsite Theft Exposure Before the Next Loss
Review how your current policies address building materials, contractor-owned tools, rented equipment, subcontractor property, theft conditions, and applicable limits before the next custom home project gets underway.
Updated October 20, 2026. Policy terms vary by insurer and coverage form. Confirm the terms of your own policy with your insurance professional.