

Insurance for Construction Companies With More at Stake
Carolina Risk Partners is an independent commercial insurance brokerage serving established construction companies across North Carolina.
We work with businesses managing multiple projects, significant payroll, subcontractors, fleets, equipment, contract requirements, and increasingly complex insurance programs. We review the program you already have, work with your current carrier when it makes sense, and create market competition when it does not.
Multiple projects, crews and subcontractors make insurance harder to manage. We review the coverage you already have, work with your current carrier when it makes sense, and explore alternatives when it doesn’t.
North Carolina Focus
Based in Wake Forest and serving construction companies across Raleigh, Durham, Cary, the Triangle, and North Carolina.
Construction Company Expertise
Projects, payroll, subcontractors, vehicles, contracts, equipment, claims, audits, and growth all matter.
More Than a Renewal Quote
Qualifying accounts receive proactive support designed around the insurance program throughout the year.
The policy being bound is the beginning, not the end.
Established construction companies keep changing after renewal. Projects change. Payroll changes. Vehicles change. Contracts show up. Audits happen. Claims happen. For qualifying accounts, our service model is designed around staying involved throughout the policy year instead of simply placing coverage and resurfacing at the next renewal.
North Carolina Construction Companies, Across Trades
General Contractors
Companies coordinating projects, subcontractors, contracts, payroll, fleets, and larger job requirements.
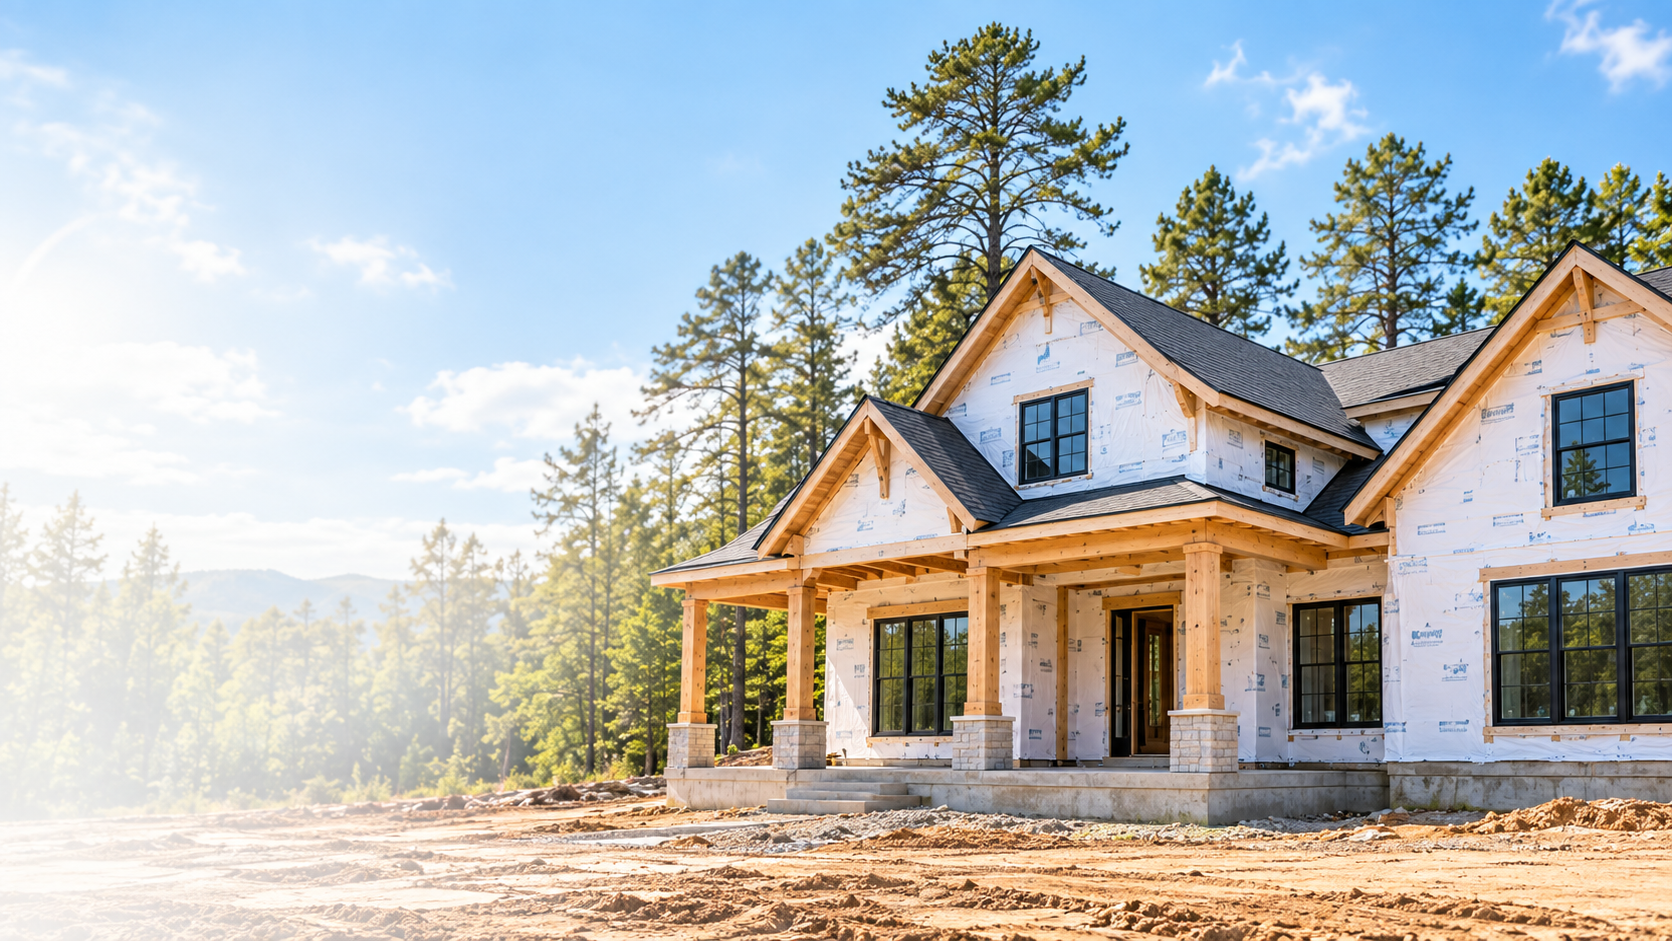
Custom Homebuilders
Established builders managing multiple projects, higher values, subcontractors, and lender requirements.
Roofing Companies
Roofing businesses dealing with vehicles, crews, subcontractors, claims, audits, and contract requirements.
Restoration Contractors
Water, fire, reconstruction, packout, vehicles, pollution, workers compensation, and specialized liability exposures.
Specialty Construction
Concrete, excavation, HVAC, landscaping, electrical, site work, and other established specialty firms.
Commercial Insurance for Construction Companies
-
General Liability
Coverage for qualifying third-party bodily injury and property damage claims, subject to policy terms, exclusions, and endorsements.
-
Workers Compensation
Coverage for qualifying employee work injuries, with pricing affected by payroll, classifications, claims, and other rating factors.
-
Commercial Auto
Coverage for company vehicles and related auto exposures, including fleets, trailers, drivers, hired auto, and non-owned auto.
-
Builder’s Risk
Property coverage for qualifying buildings, projects, and materials while construction is underway.
-
Umbrella / Excess
Additional liability limits above qualifying underlying policies for larger contracts, projects, and higher-severity exposures.
-
Tools & Equipment
Inland marine coverage can protect qualifying tools, equipment, materials, and property moving between jobsites.
-
Construction Bonds
Bid, performance, payment, license, permit, and other construction or contract bond needs.
-
Subcontractor Risk
Insurance requirements, certificates, additional insured status, waivers, contracts, audits, and risk-transfer practices.
Real Insurance Guidance for Companies With More Moving Parts
Practical Guidance
We focus on the decisions that affect your operation, projects, contracts, claims, audits, and long-term insurance program.
Current Carrier + Market Leverage
We do not assume changing carriers is the answer. We work with the incumbent when it makes sense and create competition when the account needs it.
Construction-Focused Experience
Subcontractors, certificates, contracts, fleets, payroll, projects, equipment, and audits are part of the conversation from the start.
A Clear Process From Review to Market
-
1
Understand the Business
Projects, revenue, payroll, subcontractors, vehicles, equipment, contracts, claims, and growth.
-
2
Review What You Have
Current carriers, policies, limits, endorsements, exclusions, pricing, audits, and loss history.
-
3
Identify What Needs Attention
Coverage gaps, pricing issues, classifications, contract requirements, claims, and operational changes.
-
4
Approach the Right Markets
When competition is warranted, we approach carriers that fit the operation without creating unnecessary market conflicts.
-
5
Present a Clear Strategy
Pricing, coverage, tradeoffs, carrier fit, and the recommended next step are presented clearly.
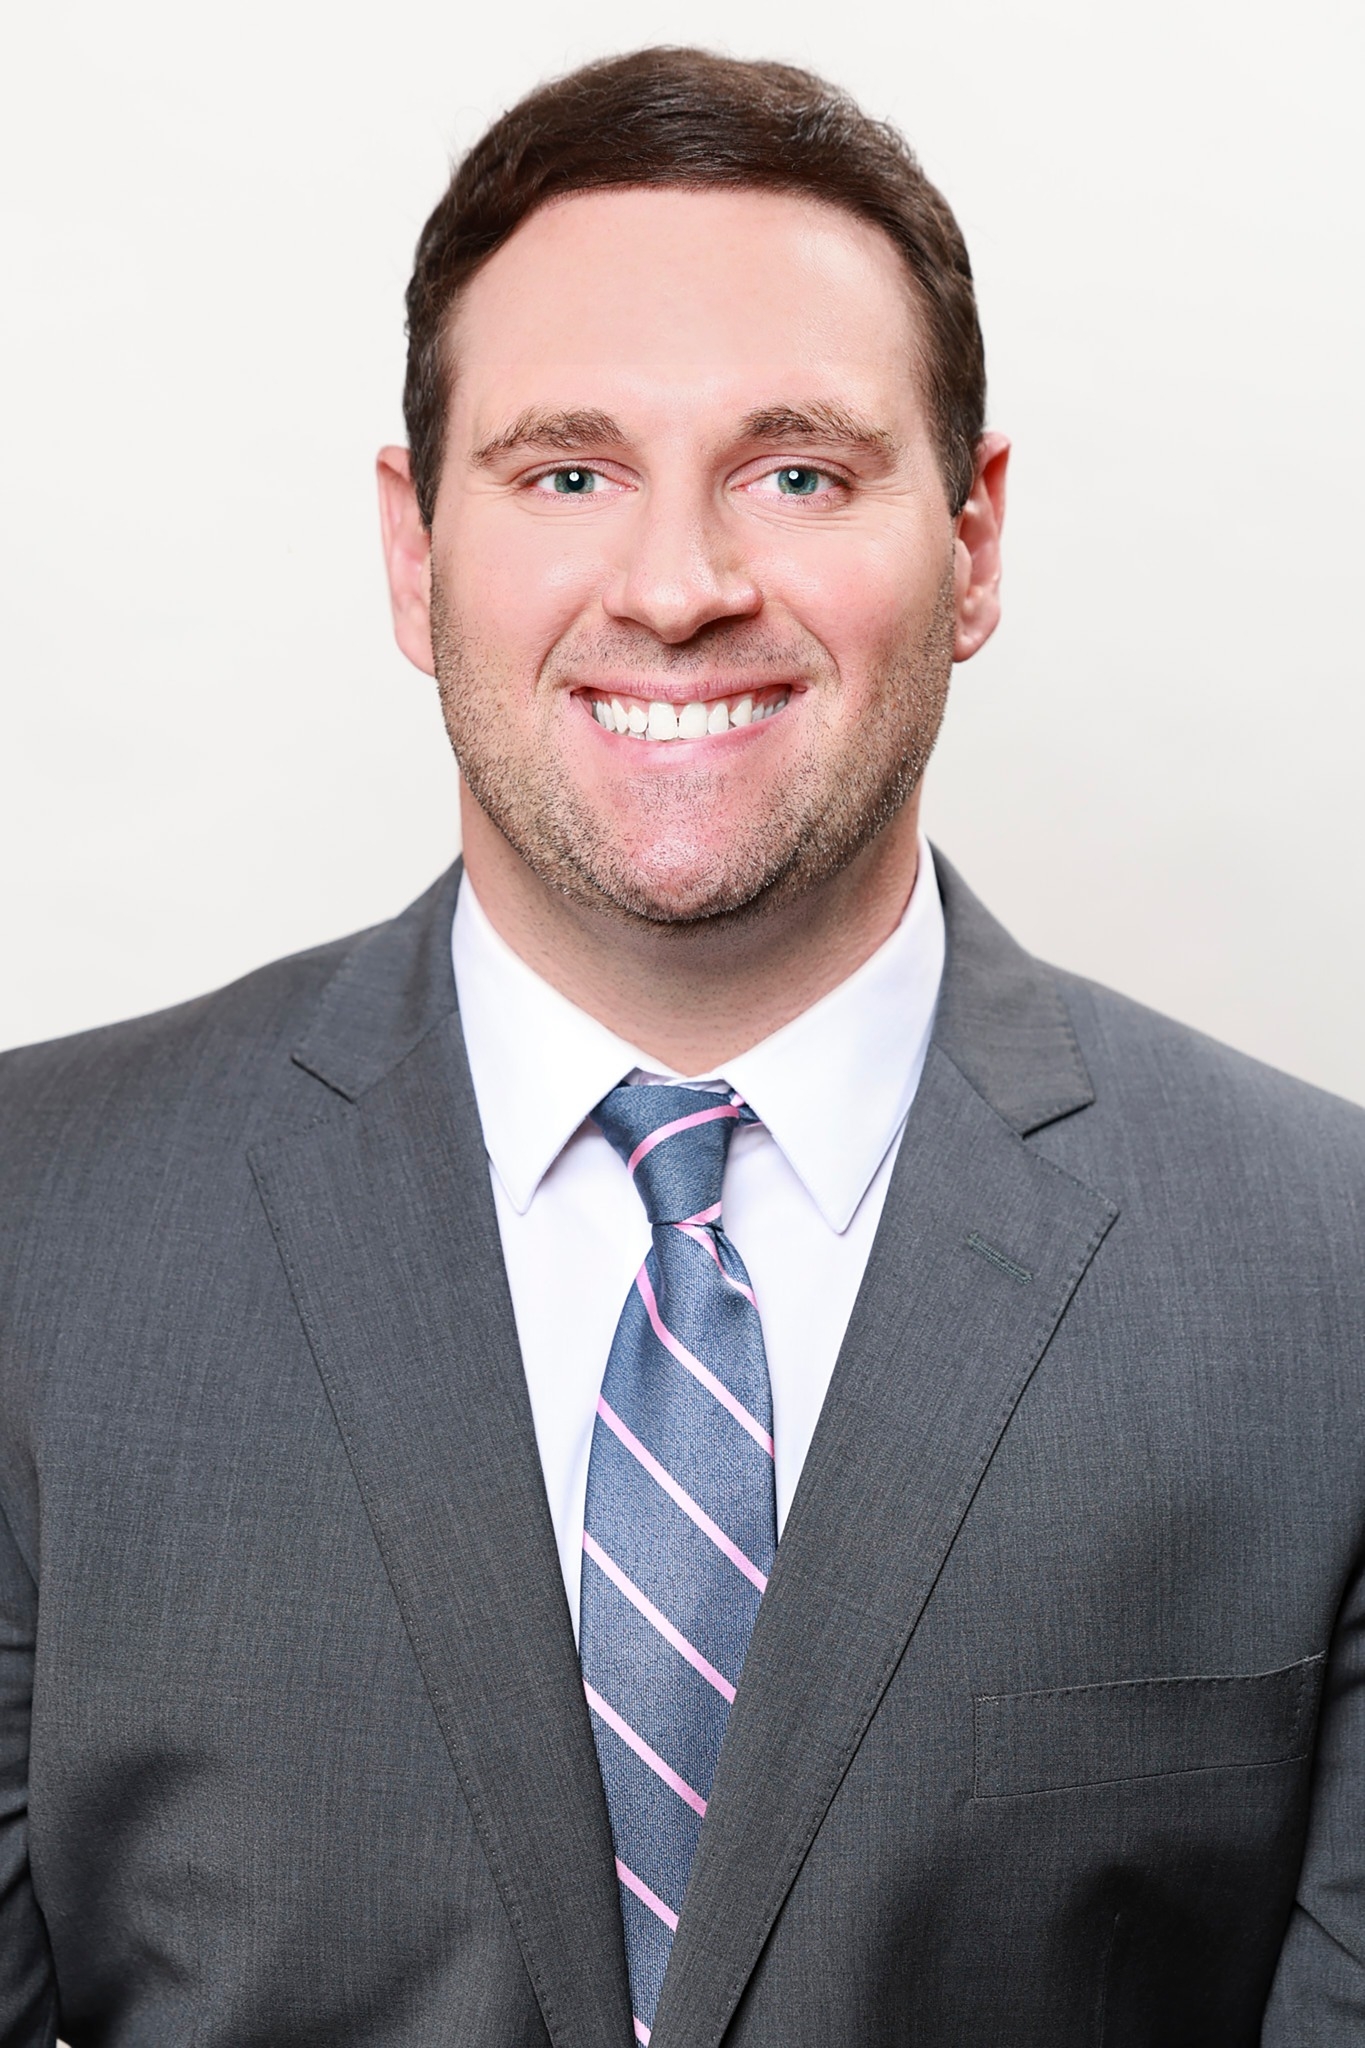
Stephen Ellias, CLCS
I work with established North Carolina construction companies to understand the insurance program they already have, identify the issues worth fixing, and determine what should happen next.
You do not need to switch carriers to start. We can begin with your current program and determine whether the right answer is to improve it, keep it, or put it under competitive pressure.
Get a second look at your construction insurance program.
Renewal, pricing, coverage, audits, claims, contracts, or operational changes are all reasonable places to start.
Common Questions About Working With Carolina Risk Partners
Do we have to change insurance carriers to get a coverage review?
No. We can start with the carrier and policies you already have. The first step is understanding the current program and deciding what, if anything, deserves to change.
What does year-round support mean?
For qualifying construction accounts, it means staying involved as meaningful insurance issues arise during the policy year, including carrier discussions, exposure changes, audits, contracts, claims activity, and renewal preparation. The exact service scope depends on the account.
Who will we actually work with?
Stephen Ellias, CLCS, is the founder of Carolina Risk Partners and is personally involved in the advisory relationship.
Make Sure Your Insurance Can Keep Up With Your Company
Start with the program you already have. We can review the carrier, coverage, pricing, renewal strategy, and operating changes before deciding what deserves to move.